Equity toward your down payment
Several of our clients built with little or no cash down this way, including the three stories below.
You already own the land
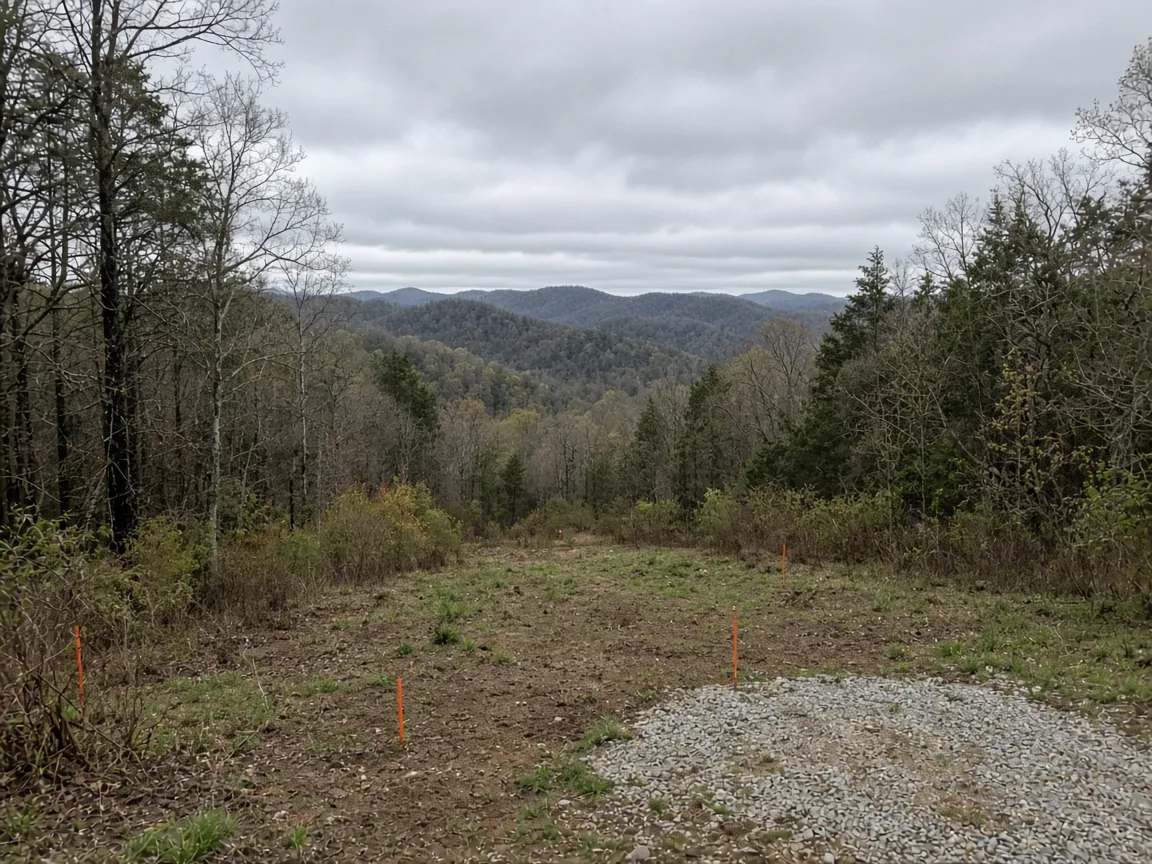
Owning your land is a real head start. Its equity can often count toward your down payment, and we'll help you confirm the land is ready before you spend money on plans.
Your head start
Family land, inherited land, a lot you paid off years ago. We see all of these every week, and owning your land is a real advantage.
Land equity can cover some, most, or occasionally all of what you'd otherwise bring to closing. How much depends on the appraised value, anything still owed, and your loan program.
Several of our clients built with little or no cash down this way, including the three stories below.
Your construction and your permanent mortgage are covered together, with one set of closing costs.
Since you're not buying land, you may borrow less, which can mean a more comfortable payment.
Before you spend money on plans
A few things can stop a build that looked fine on paper: no water source, soil that fails a perc test, no legal road access, or flood risk. Better to find these before you pay for plans or a deposit.
We'll go over these with you on the first call, so you know what's confirmed and what still needs checking.
What we look at
Most of these are quick to confirm, and some may already be settled. Here's what we look at together:
Buying a second parcel to combine with land you already own? See land and home together.
Your first call
You don't need everything on this list. Bring what you have, and we'll tell you what still needs to be confirmed:
Every NewBuild loan follows the same six steps, from your first call to Move-In Day. It starts with a free consultation, and no house plans are needed.
Real builds
Three clients who used land they already owned, one with each loan program.
Manufactured · Kingsport, TN
Land he already owned covered his closing costs, so he financed a roughly $220,000 manufactured home with no money due at closing.
Tyler, a younger veteran, already owned land that had been gifted to him and wanted to place a new double-wide on it while keeping his existing home for the time being. The land's value offset the closing costs and prepaid items, letting him complete a roughly $220,000 VA one-time-close loan without bringing money to closing. When an unexpected issue came up running power to the new home, the construction loan funded that work through a direct payment to the local power board rather than routing it through the dealer. Tyler completed the home while keeping the flexibility to sell or rent his previous residence afterward.
Modular · Tazewell, TN
Using the land they already owned as their down payment, Ken and Connie financed a roughly $327,000 modular home with one FHA loan.
Ken and Connie were ready to leave California and build on land they already owned in Tazewell, Tennessee. Working with Clayton Homes of Kingsport, they chose a modular home and started the financing process with a bank in Kentucky, but communication was poor and their calls eventually went unreturned. That's when they reached out to us. Since Connie works remotely, the move didn't mean giving up her job, and the couple handled much of the process from across the country. Their land's value served as their down payment rather than cash savings. They completed their FHA one-time-close loan, made the move east, and are now settled into their new home.
Manufactured · Dungannon, VA
Ty used land he inherited as his down payment and financed a roughly $316,000 manufactured home with one conventional loan.
Ty came to us through a referral and chose to work with us because of our communication and pricing. He had inherited land in Dungannon, Virginia, and wanted to place a new manufactured home on it through Clayton Homes of Kingsport. Because the land needed to be split, a new survey was required, and between some early delays and a survey that took about three months to complete over the winter, the process stretched to roughly nine months from our first conversation to closing. Ty stayed patient, his inherited land served as his down payment, and he's now living in his new home.
Names have been changed to protect client privacy. Loan amounts and details are real but reflect each borrower's individual credit, income, and underwriting circumstances; results aren't typical or guaranteed for every applicant.
Your guide
Building on your own land has more moving parts than a regular purchase. Our five-person team handles all of it, from your first call to your final draw.
Your loan program
Veterans usually start with VA. FHA fits a smaller down payment, and conventional fits strong credit and a down payment. We'll help you choose on your first call.
Related situations: Veterans Without a big down payment Good credit and a down payment First time building
FAQ
Often, yes. Your land's equity can count toward your down payment, and sometimes cover most or all of it. How much depends on the land's appraised value, anything owed on it, your loan program, and the rest of your project cost.
It's common, and it's often fixable. Clearing up the title just becomes the first step. Bring whatever paperwork you have, and we'll tell you what's needed to move forward.
Not always. If you still owe on it, the payoff becomes part of the picture and can change your cash to close. Just let us know what's owed on your first call.
Then the land may need a different type of septic system, or it may not support the home you had in mind. That's a site question before it's a loan question, and it's much better to learn it before you pay a deposit.
We offer construction loans in Tennessee, Virginia, North Carolina, South Carolina, Georgia, and Kentucky. Your land needs to be in one of those states. Find your area on where we serve.
A free consultation is 20 minutes. We cover your land, your eligibility, and the right loan structure. No application required.
Tennessee · Virginia · North Carolina · South Carolina · Georgia · Kentucky
20 minutes · no application · no commitment
NewBuild is led by the Arrowood Team at Preferred Rate. 260+ five-star Google reviews.
Prefer to reach out directly?