A sited manufactured home with a porch on a few rural acres

Good credit and a down payment

Building can be one clean process.

With strong credit and a down payment, you have options, including your own bank. What you want is one clear path: one loan, one closing, and no surprises.

One closingNo re-qualifying after the build
Two-time close tooWhen it's the better fit
Conventional limit$832,750 in most of our counties
Six statesTN · VA · NC · SC · GA · KY

A fair question

Why not just use your own bank?

You can. Many banks use two loans, a construction loan and then a separate mortgage, which means two closings, two sets of costs, and qualifying again when the home is done.

When you compare quotes, ask whether the number you heard includes the second closing, or only the construction part. We offer both structures ourselves, and we'll lay them side by side for you.

One-time closeTwo-time close
ClosingsOne, before constructionTwo, before and after construction
Closing costsOne setTwo sets
QualifyingOnce, up frontAgain after the build

What we hear

What capable buyers worry about

Even well-qualified buyers are usually new to construction loans. The worries we hear most: hidden or duplicate costs, getting stuck partway through the build, and feeling rushed into decisions.

What you want is simple: a new home you're proud of, a payment you're comfortable with, and someone who's still there after closing.

How we help

What we look at together

We look at your whole project before you commit, not just the price of the house:

  • Your payment target. What you want your monthly payment to be.
  • Your down payment and land. Cash, land you already own, or both.
  • The complete cost. The home, the land, and site work like the well, septic, and driveway.
  • The finished value. Whether the completed home is likely to appraise for enough to support the project.
  • Your builder or dealer. Their licensing, insurance, and experience with construction loans.
  • The loan limit. In most of the counties we serve, the 2026 conventional limit is $832,750 for a one-unit home. It applies to the loan amount, not your total project cost.

A larger down payment can support a larger project. For bigger or longer builds, a two-time close may be the better fit, and we'll walk through both options with you before you spend time or money on plans.

The NewBuild System

Your build, step by step

Every NewBuild loan follows the same six steps, from your first call to Move-In Day. It starts with a free consultation, and no house plans are needed.

  1. Build Plan Consultation

  2. Pre-Approval

  3. Plan and Contract Review

  4. Loan Closing

  5. Construction

  6. Move-In Day

Real builds

Conventional clients who built with one loan

Two conventional one-time close loans we've closed, both on land the borrowers already owned.

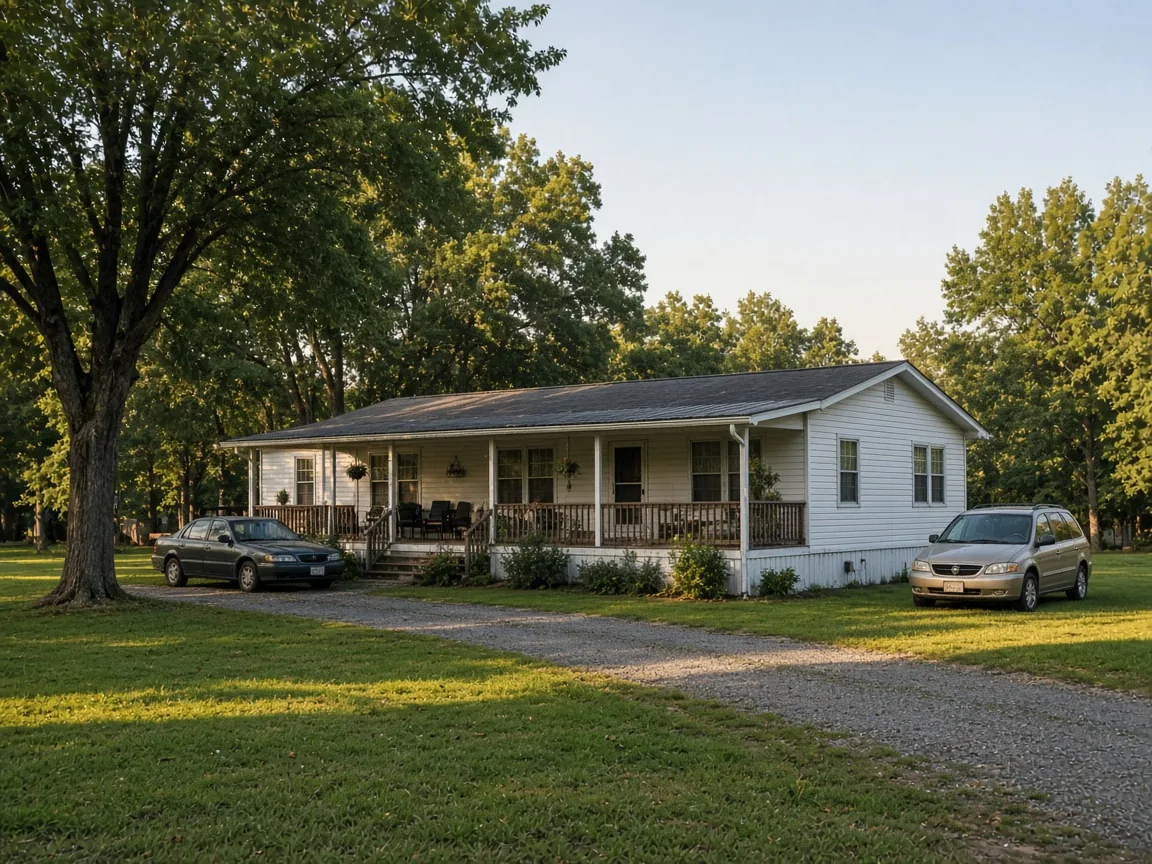
Manufactured · Johnson City, TN

Owning her land outright gave her a head start on a smaller loan.

Between land she owned free and clear and some extra cash, Lydia put about 50% down on a roughly $234,000 manufactured home project.

Read their story

Lydia came to us through a referral from a realtor friend, ready to place a new manufactured home on land she already owned free and clear. She chose her home through Preferred Choice Homes of Johnson City, and with strong qualifications, a conventional one-time-close loan was a natural fit. Her land's value went toward the down payment, and she chose to add some of her own cash on top of it, bringing her total down payment to about half the project's value. That left her with a relatively small loan amount and a payment she felt good about.

Lydia M. · Conventional one-time-close construction borrower, Johnson City, TN · Builder: Preferred Choice Homes of Johnson City (opens in a new tab)

Manufactured · Dungannon, VA

A winter survey slowed things down, but his inherited land still made the down payment.

Ty used land he inherited as his down payment and financed a roughly $316,000 manufactured home with one conventional loan.

Read their story

Ty came to us through a referral and chose to work with us because of our communication and pricing. He had inherited land in Dungannon, Virginia, and wanted to place a new manufactured home on it through Clayton Homes of Kingsport. Because the land needed to be split, a new survey was required, and between some early delays and a survey that took about three months to complete over the winter, the process stretched to roughly nine months from our first conversation to closing. Ty stayed patient, his inherited land served as his down payment, and he's now living in his new home.

Ty N. · Conventional one-time-close construction borrower, Dungannon, VA · Builder: Clayton Homes of Kingsport (opens in a new tab)
Names have been changed to protect client privacy. Loan amounts and details are real but reflect each borrower's individual credit, income, and underwriting circumstances; results aren't typical or guaranteed for every applicant.

Your guide

One team, start to finish

  • Tim Arrowood
  • Cindy Faulkner
  • Kevin Cooper
  • Rhonda Hendrix
  • Amy Lay

A construction loan has more moving parts than a regular purchase. Our five-person team handles all of it, from your first call to your final draw.

260+ five-star reviews Since 2023 closing one-time close loans Our team stays with you through every draw

Other options

Is conventional the right fit?

Conventional works well for site-built, modular, and manufactured homes when you have strong credit and a down payment.

If you served, start with VA. For a smaller down payment or more budget room, compare FHA. We'll help you weigh them.

Related situations: Site-built home Manufactured home You already own the land First time building

FAQ

Frequently asked questions

Aren't your costs higher than the bank down the road?

Compare the whole structure, not just the first closing. A two-time close loan can look less expensive until the second set of closing costs arrives. We'll put both side by side so you can see the full picture.

How complicated is this going to be?

A construction loan has more moving parts than buying an existing home. The point of one-time close is that you don't have to manage all of it yourself. We'll walk you through each step and stay with you through the draws.

Is there a limit on how much I can borrow?

Yes. In most of the counties we serve, the 2026 conventional limit is $832,750 for a one-unit home. The limit applies to the loan amount, not your total cost, so a larger down payment can support a larger project.

Do you offer two-time close construction loans?

Yes. Most of our clients choose one-time close, but we also offer a conventional two-time close for specific situations, like keeping your current home until the new one is finished, or a larger, longer project. It requires at least 10% down. We'll look at both with you on your first call.

Does conventional work for manufactured homes?

Yes, when the home sits on a permanent foundation and is titled as real property together with land you own or are buying. Plenty of buyers with strong credit choose a manufactured home on purpose, for the space and cost control.

Your land. Your build. Let's talk it through.

A free consultation is 20 minutes. We cover your land, your eligibility, and the right loan structure. No application required.

Tennessee · Virginia · North Carolina · South Carolina · Georgia · Kentucky

Schedule a Free Consultation (opens in a new tab)

20 minutes · no application · no commitment

NewBuild is led by the Arrowood Team at Preferred Rate. 260+ five-star Google reviews.

Prefer to reach out directly?

(423) 406-1567 · newbuild@preferredrate.com