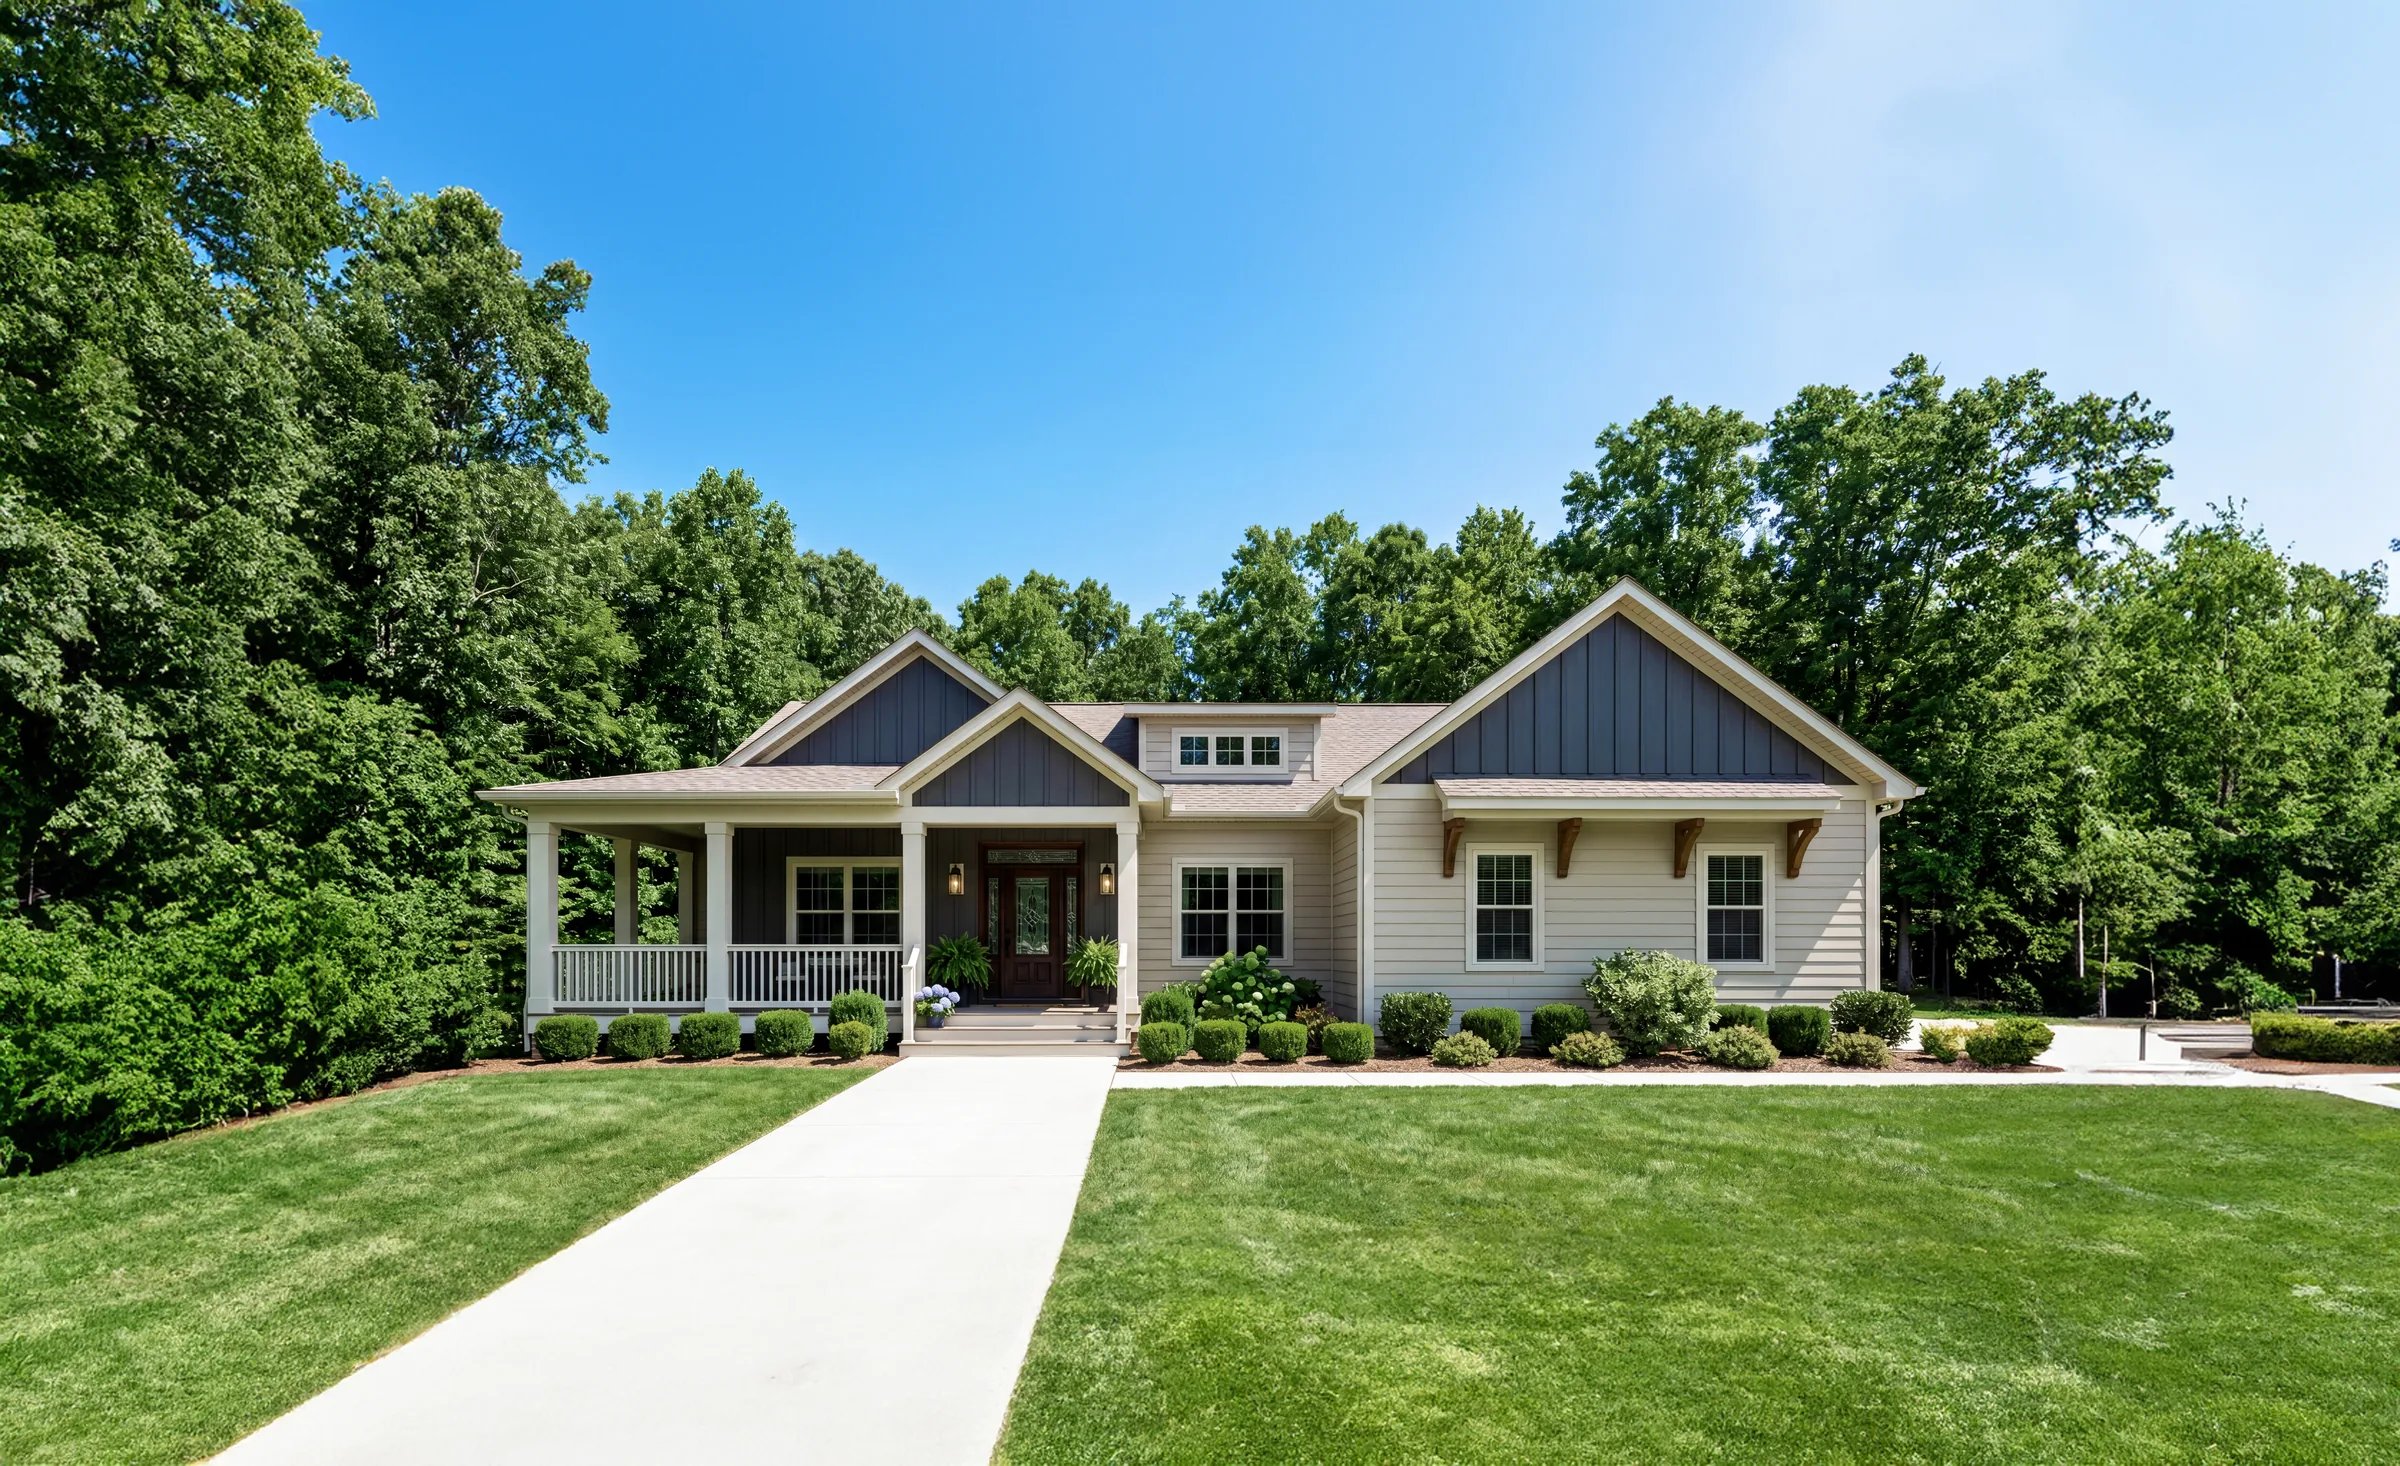
Manufactured · modular · financed as real property
Manufactured and modular home construction loans
Finance your manufactured or modular home and your land together, as real property, with one loan and one closing.
Your home, land, and site work in one loan
VA, FHA, and conventional options
A team that works with your dealer through the final draw
or call (423) 406-1567 · 20 minutes · no application required
Why this matters
Your home should be financed like a home
Many lenders treat a manufactured home like a vehicle instead of a house. They finance it as personal property, often called a chattel loan, which often comes with higher rates and shorter terms. And many purchase lenders don't offer construction financing for manufactured or modular homes at all.
That's exactly the work we specialize in. When your home sits on a permanent foundation on land you own or are buying, it can be financed together with your land, just like a site-built home.
The basics
Manufactured vs. modular homes
The two words get used interchangeably, but lenders and appraisers treat them differently. Here's how they compare.
| Manufactured | Modular | |
|---|---|---|
| Built to | The federal HUD Code for manufactured housing | The same state and local building codes as site-built homes |
| Labeled with | A HUD certification label on each section | State certification where required, like Virginia's Industrialized Building Certificate |
| Delivered | On its own permanent chassis, then set on site | In sections, set on a foundation, often by crane |
| Financed with a one-time close loan | Yes, on a permanent foundation, titled with the land | Yes, on a permanent foundation, titled with the land |
What makes it a real-property loan
A permanent foundation
The foundation has to meet program requirements, and it often needs an engineer's certification. Make sure your dealer's setup quote includes the right foundation before you pay a deposit.
Home and land titled together
The home and land are titled together as real property, following your state's process. We'll walk you through what your state requires.
Land you own or are buying
The land can be land you already own, or land you buy as part of the same loan. Homes on rented land, including mobile home parks, are financed differently.
Your manufactured or modular home loan, step by step
Every NewBuild loan follows the same six steps, from your first call to Move-In Day. It starts with a free consultation, and no house plans are needed.
Build Plan Consultation
Pre-Approval
Plan and Contract Review
Loan Closing
Construction
Move-In Day
Real builds
Manufactured and modular homes we've financed
Names have been changed to protect client privacy. Results reflect each borrower's individual circumstances and aren't typical or guaranteed.
Plan ahead
What can slow things down, and how we help
- Foundation that doesn't meet requirements? We confirm the foundation requirements early, so your dealer's setup quote matches what the loan needs.
- Tight or steep access for delivery? We help you plan driveway and site work costs from the start.
- Splitting land or a new survey? We help you spot what's needed early.
- Septic, well, and utilities? We include them in your loan, so there are no surprises at setup.
Choose your program
Loan programs for manufactured and modular homes
VA construction loan
For eligible veterans and active duty. Can finance a manufactured or modular home on a permanent foundation when the home and property meet VA requirements.
Explore VA construction
FHA construction loan
A common path for manufactured and modular homes, with a lower down payment and more flexible credit.
Explore FHA construction
Conventional construction loan
For strong credit and a down payment. Our conventional clients have financed manufactured homes on land they owned.
Explore conventional constructionYour guide
One team, start to finish
Manufactured and modular loans have more moving parts than a regular purchase. Our five-person team handles all of it, from your first call to your final draw.
FAQ
Frequently asked questions
Can a manufactured home be financed as real property?
Yes, when the home sits on a permanent foundation that meets program requirements and is titled together with land you own or are buying. That's what lets it be financed with a one-time close construction loan, like a site-built home.
Can I use a VA loan on a manufactured home?
Yes. VA can finance a manufactured or modular home on a permanent foundation on land you own or are buying, when the home and property meet VA requirements. Several of our VA clients have built this way. See VA construction loans.
My dealer said the loan pays them 100% at delivery. Is that right?
No. Construction loans pay in stages. For manufactured and modular homes, the usual schedule is 10% at closing, 80% when the home is delivered, and 10% at completion. Most dealers we work with already know this, and we're glad to talk it through with yours.
Can I put a manufactured home on land I already own?
Yes, and it's one of the most common ways our clients build. Your land's equity may even count toward your down payment. See building on land you own.
Can I buy the land and the home together?
Yes. A one-time close loan can include the land purchase, the home, the site work, and your permanent mortgage, all in one closing. Dealers often call this a land-home package.
Can you finance a home in a mobile home park or on rented land?
No. Our one-time close loans are for homes on land you own or are buying, financed together as real property. Homes on rented land are financed differently.
We don't publish rates or APRs on this site, because your terms depend on your situation. All loans are subject to credit approval and underwriting. Equal Housing Opportunity.
Your land. Your build. Let's talk it through.
A free consultation is 20 minutes. We cover your land, your eligibility, and the right loan structure. No application required.
Tennessee · Virginia · North Carolina · South Carolina · Georgia · Kentucky
20 minutes · no application · no commitment
NewBuild is led by the Arrowood Team at Preferred Rate. 260+ five-star Google reviews.
Prefer to reach out directly?