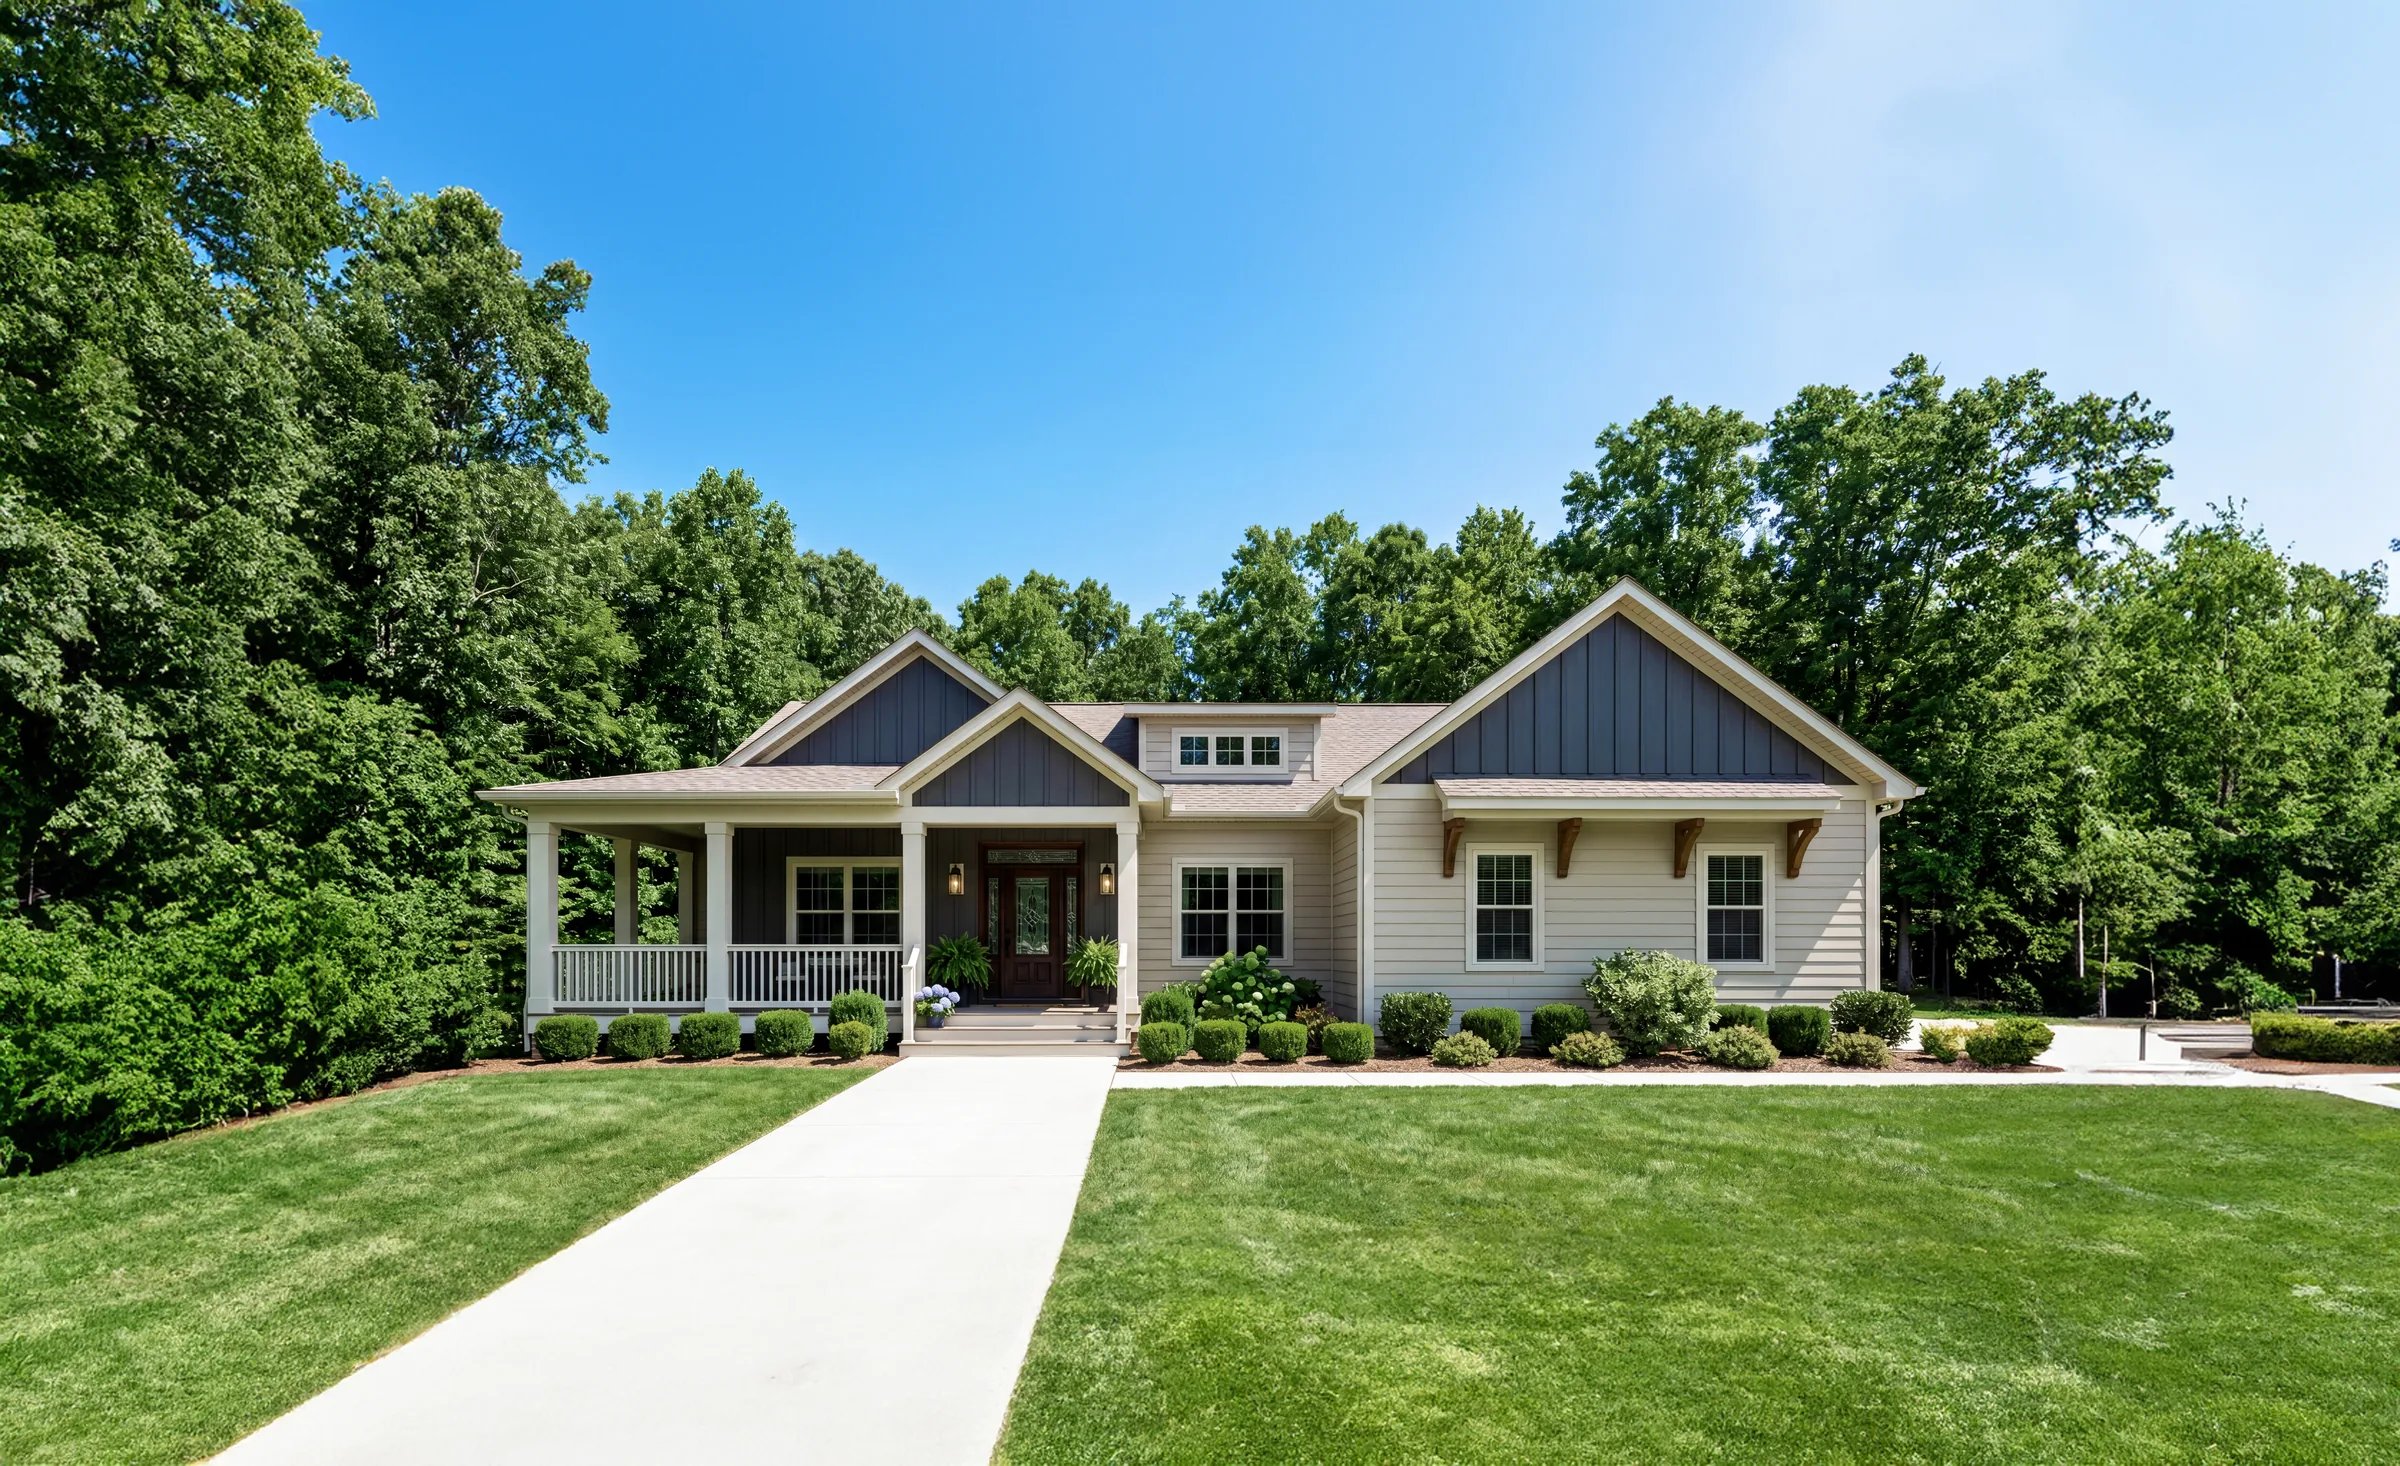
VA · FHA · Conventional
Construction loan programs
- Site-built
- Modular
- Manufactured
One loan covers your land, the construction, and your permanent mortgage, with a single set of closing costs. Not sure which program fits? Start with a free 20-minute consultation.
Choose your program
Which loan fits your build?
VA construction loan
For eligible veterans and active duty. Often no down payment, no monthly PMI, and one closing.
Explore VA construction
FHA construction loan
When cash is tighter. A lower down payment and more flexible credit, for buyers who don't have 20% saved.
Explore FHA construction
Conventional construction loan
For stronger credit and a real down payment. Often a fit for higher loan amounts and custom builds.
Explore conventional constructionBuilding something specific? Barndominium Manufactured or modular First time building
Not sure which fits? A free consultation (opens in a new tab) matches your situation to the right program.
Same moving parts
Three programs, one process
No matter which loan you choose, every construction project has to solve the same pieces: land, house, site work, your builder or dealer, appraisal, closing, and draws. What changes between VA, FHA, and conventional is how much cash you bring, which lender requirements apply, and whether VA's stricter occupancy rules come into play.
Every loan follows the same six steps
Every NewBuild loan follows the same six steps, from your first call to Move-In Day. It starts with a free consultation, and no house plans are needed.
Build Plan Consultation
Pre-Approval
Plan and Contract Review
Loan Closing
Construction
Move-In Day
FAQ
Frequently asked questions
Which loan program is right for me?
Veterans typically start with VA. If you're not a veteran, FHA is often the better fit when cash is tight, and conventional works well with stronger credit and a larger down payment. If you're not sure, a free consultation (opens in a new tab) will help you land on the right one.
Why don't you publish rates?
The right structure depends on your occupancy, entitlement, cash, and credit, not a table, so a published rate would rarely match your situation. A free consultation (opens in a new tab) gives you real numbers, and the cost planner can give you an early estimate of total project cost.
Can I switch programs mid-build?
Program choice needs to happen before you sign a house contract, not partway through. That's why we recommend starting with a consultation if you're unsure, rather than picking and switching later.
Where do you offer construction loans?
Tennessee, Virginia, North Carolina, South Carolina, Georgia, and Kentucky. Browse by state or city on where we serve, and we'll cover your specific county on your call.
Can you provide my permanent loan if my construction loan is with another lender?
Yes. If your construction loan is with another lender, we can help with your permanent loan, sometimes called a takeout loan, when your home is finished. It can be conventional, FHA, or VA, depending on your situation. Give us a call before construction wraps up, so there's time to get everything ready. See refinancing after you build.
Your land. Your build. Let's talk it through.
A free consultation is 20 minutes. We cover your land, your eligibility, and the right loan structure. No application required.
Tennessee · Virginia · North Carolina · South Carolina · Georgia · Kentucky
20 minutes · no application · no commitment
NewBuild is led by the Arrowood Team at Preferred Rate. 260+ five-star Google reviews.
Prefer to reach out directly?