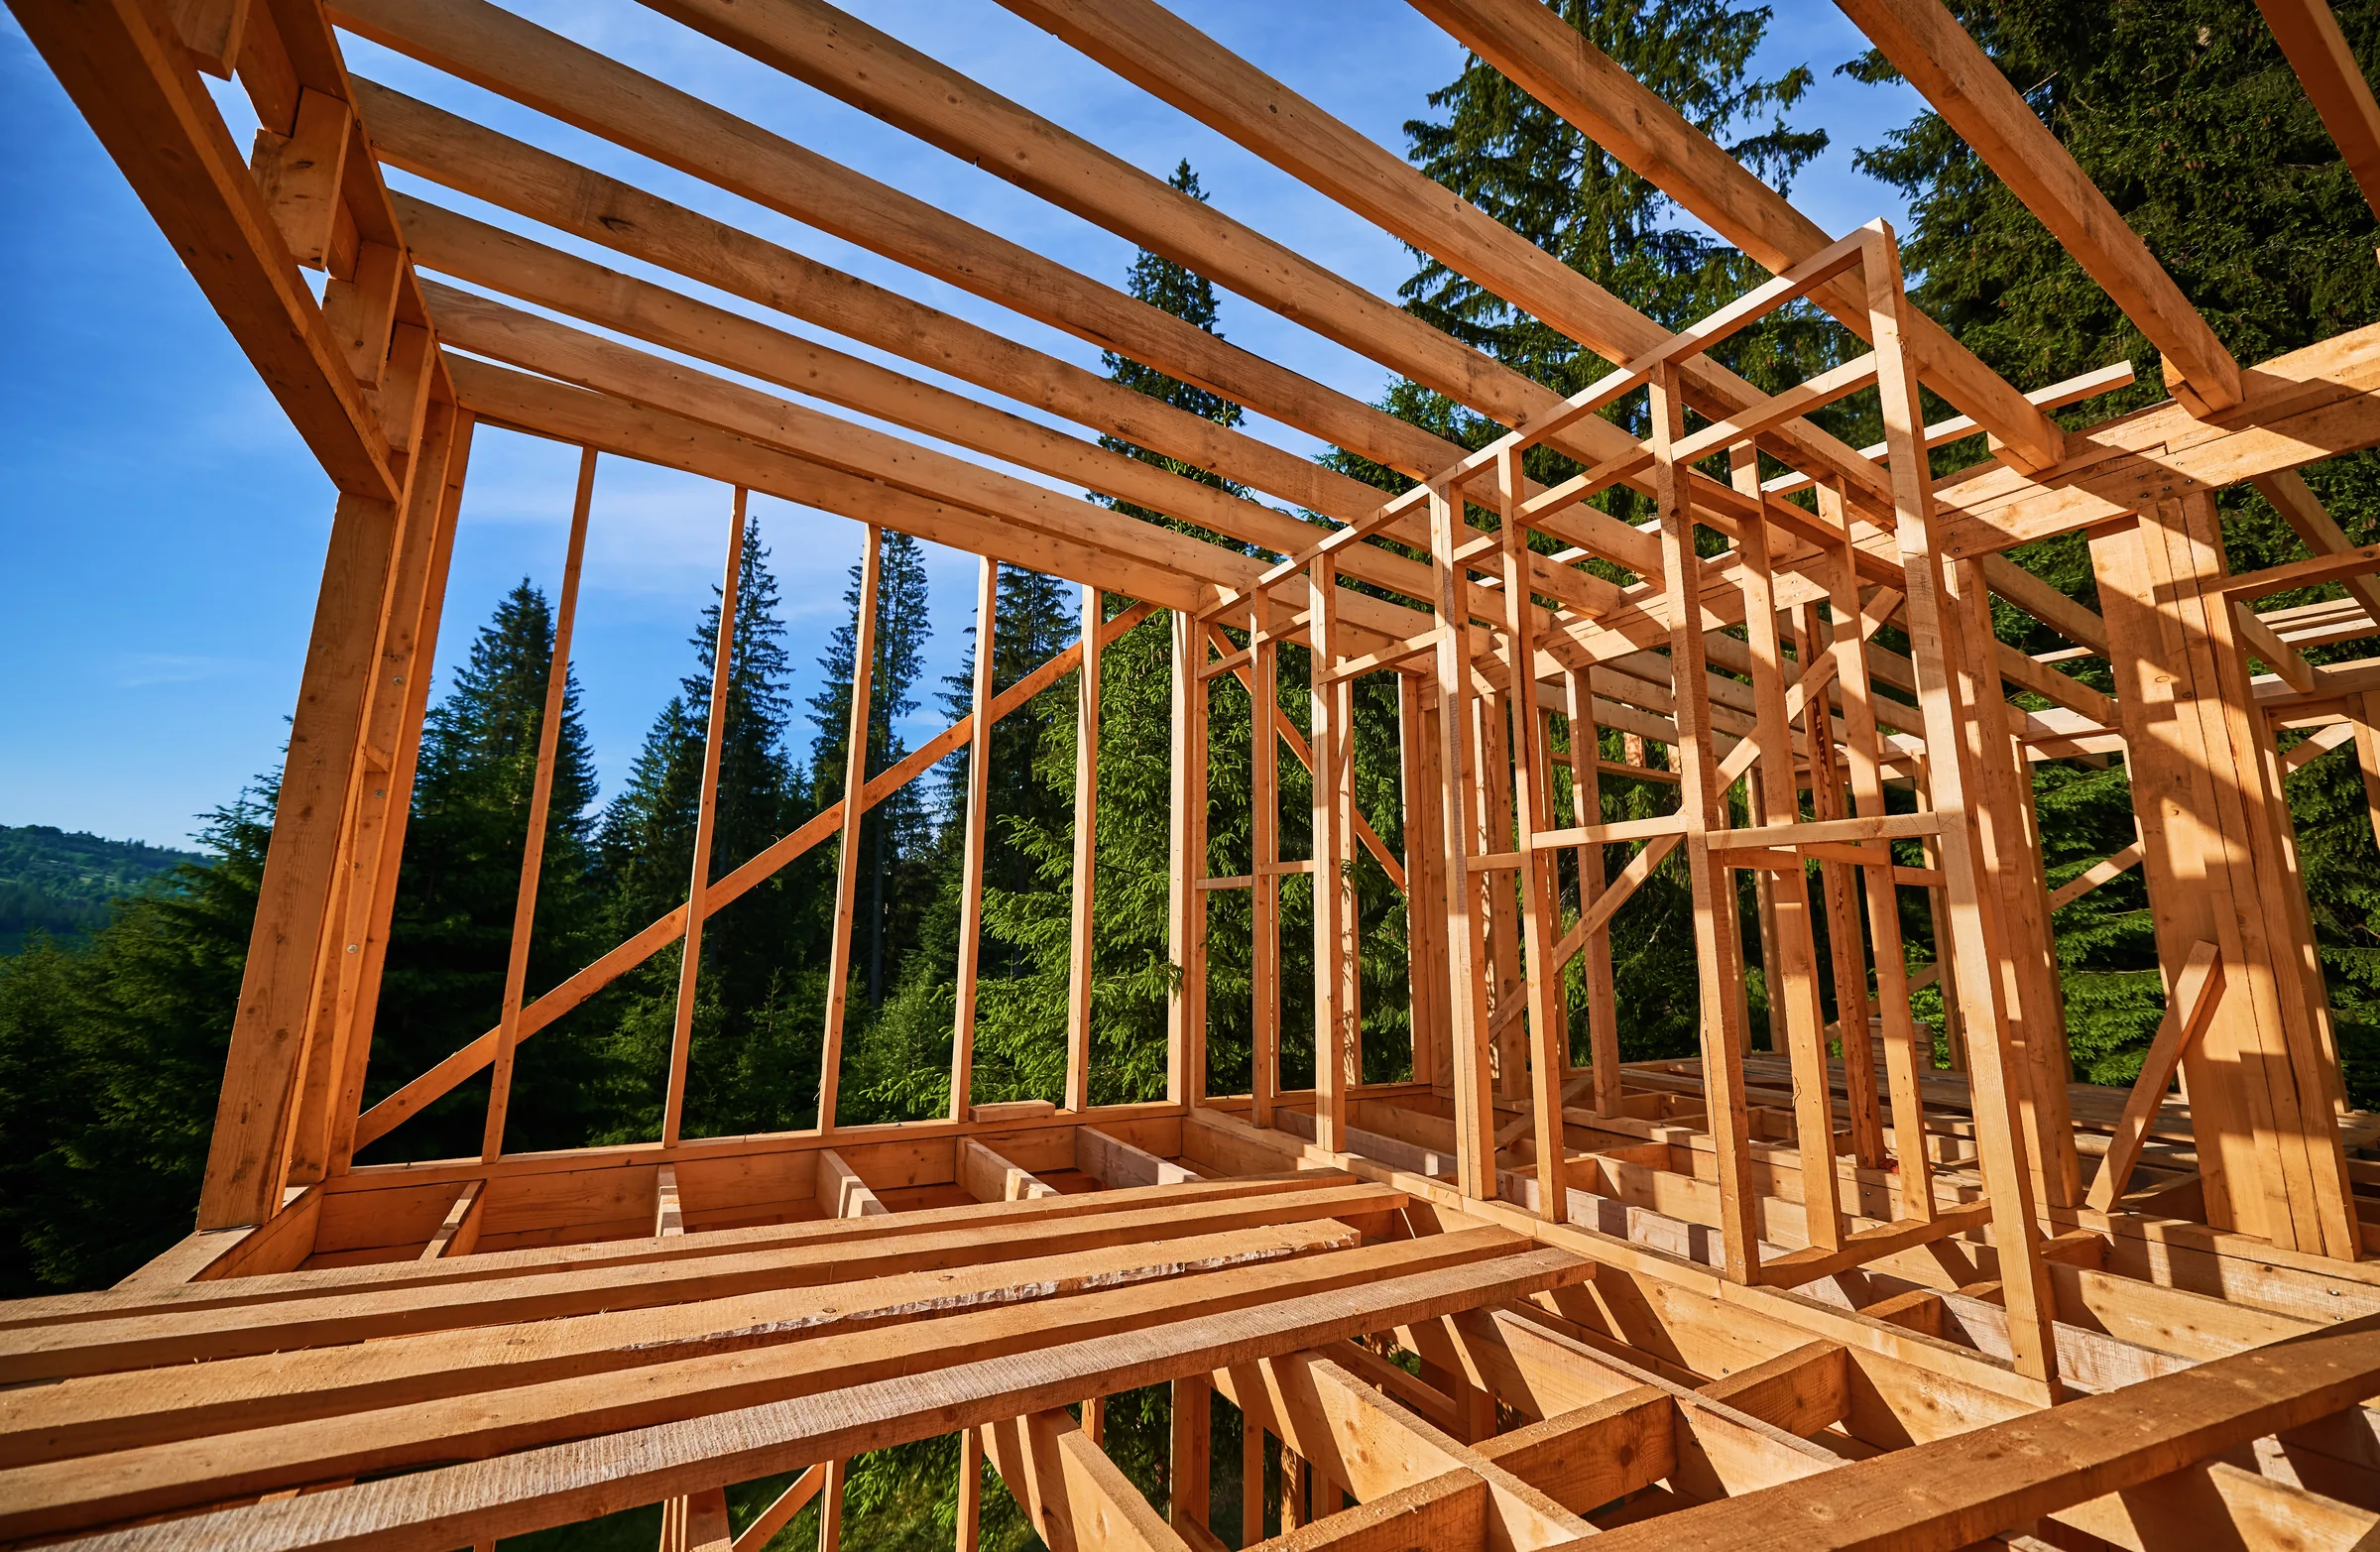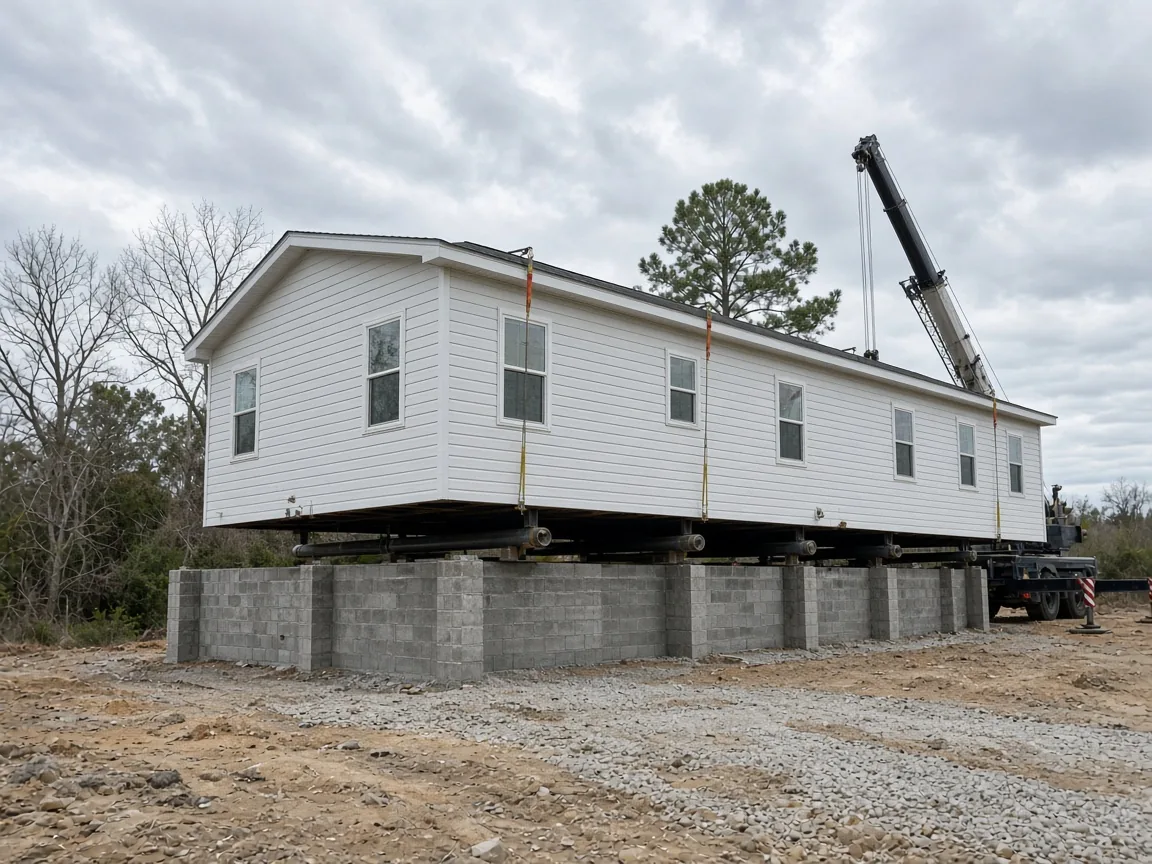
A manufactured home being set onto a permanent foundation on a rural pad

Manufactured home

A manufactured home on your land, financed like a house.

Today's manufactured homes are a smart way to get a brand-new home on your own land. Financed with the land as real property, you get a real mortgage, with one loan and one closing.

Real propertyYour home and land, financed together
Work with your dealerWe handle the financing and draws
Any of our programsVA, FHA, or conventional
Six statesTN · VA · NC · SC · GA · KY

A smart choice

Today's manufactured homes have come a long way

Today's manufactured homes are built indoors in modern factories to federal construction standards, with open floor plans, updated kitchens and baths, and finishes you'd expect in any new home. Many offer energy-efficient features too.

And for the space and quality you get, their value is hard to beat. Many of our clients get more home for their budget than they could with a new site-built home, on land they love.

Your dealer may be how you found us, and that's great. They'll handle your home, delivery, and setup. We handle the financing and the draws, so that's one less thing for your dealer, and you, to chase.

What to watch for

What people often get wrong on the lot

That the price on the sign is the whole cost. That any foundation will do. That "we finance" on a banner means a construction loan for your home and land together. Or that upgrades added later won't affect the appraisal.

We bring these up early, before you choose upgrades that could leave a gap between the price and the appraised value.

The requirements

What it takes to finance it as real property

For your manufactured home to be financed with a mortgage, a few things need to be true:

  • Land you own or are buying. Your home and land are financed together.
  • A permanent foundation. One that meets your loan program's requirements, often with an engineer's certification.
  • Home and land titled together. Following your state's process for real property.
  • A dealer who completes the setup. Including the foundation, utilities, and finishing work.

A home on rented land, like a mobile home park, uses a different kind of loan, often called a chattel loan. Already have one? See refinancing.

Want the details on foundations, titling, and how draws work with your dealer? See manufactured and modular home loans.

The NewBuild System

Your manufactured home, step by step

Every NewBuild loan follows the same six steps, from your first call to Move-In Day. It starts with a free consultation, and no house plans are needed.

  1. Build Plan Consultation

  2. Pre-Approval

  3. Plan and Contract Review

  4. Loan Closing

  5. Construction

  6. Move-In Day

Real builds

Manufactured homes we've financed

Three manufactured homes, one with each loan program.

Manufactured · Kingsport, TN

His land equity helped him build with no money due at closing.

Land he already owned covered his closing costs, so he financed a roughly $220,000 manufactured home with no money due at closing.

Read their story

Tyler, a younger veteran, already owned land that had been gifted to him and wanted to place a new double-wide on it while keeping his existing home for the time being. The land's value offset the closing costs and prepaid items, letting him complete a roughly $220,000 VA one-time-close loan without bringing money to closing. When an unexpected issue came up running power to the new home, the construction loan funded that work through a direct payment to the local power board rather than routing it through the dealer. Tyler completed the home while keeping the flexibility to sell or rent his previous residence afterward.
Tyler V. · VA one-time-close construction borrower, Kingsport, TN · Builder: Clayton Homes of Johnson City (opens in a new tab)

Manufactured · Rutledge, TN

Splitting their land added time, but it didn't stop their build.

Pete and Susan carved a homesite out of land they already owned and are building a roughly $284,000 manufactured home with one FHA loan.

Read their story

Pete came to us through a referral after working with four or five manufactured home dealers before landing on Clayton Homes of Alcoa. He and Susan owned a few acres with a small, older home already on the property, so they had the land surveyed and divided off a portion for their new home to sit on. Underwriting and the appraisal went smoothly, but the new survey brought several county reviews and sign-offs that took longer than anyone expected. Nobody did anything wrong; the process simply took time. Pete and Susan are now under construction on their FHA one-time-close loan.

Pete and Susan G. · FHA one-time-close construction borrowers, Rutledge, TN · Builder: Clayton Homes of Alcoa (opens in a new tab)

Manufactured · Johnson City, TN

Owning her land outright gave her a head start on a smaller loan.

Between land she owned free and clear and some extra cash, Lydia put about 50% down on a roughly $234,000 manufactured home project.

Read their story

Lydia came to us through a referral from a realtor friend, ready to place a new manufactured home on land she already owned free and clear. She chose her home through Preferred Choice Homes of Johnson City, and with strong qualifications, a conventional one-time-close loan was a natural fit. Her land's value went toward the down payment, and she chose to add some of her own cash on top of it, bringing her total down payment to about half the project's value. That left her with a relatively small loan amount and a payment she felt good about.

Lydia M. · Conventional one-time-close construction borrower, Johnson City, TN · Builder: Preferred Choice Homes of Johnson City (opens in a new tab)

Names have been changed to protect client privacy. Loan amounts and details are real but reflect each borrower's individual credit, income, and underwriting circumstances; results aren't typical or guaranteed for every applicant.

Your guide

One team, start to finish

  • Tim Arrowood
  • Cindy Faulkner
  • Kevin Cooper
  • Rhonda Hendrix
  • Amy Lay

A manufactured home loan has more moving parts than a regular purchase. Our five-person team handles all of it and works directly with your dealer, from your first call to your final draw.

260+ five-star reviews Since 2023 closing one-time close loans Our team stays with you through every draw

Your loan program

Any of our programs can work

VA, FHA, and conventional loans can all finance a manufactured home on a permanent foundation. Owning or buying your land often affects your cash to close more than the floor plan does.

Related situations: You already own the land Land and home together Veterans Without a big down payment Modular home

FAQ

Frequently asked questions

Can you finance a manufactured home together with land?

Yes, when it's financed as real property: on land you own or are buying, on a permanent foundation, and titled together with the land.

Is this the same as the financing offered at the dealership?

Usually not. Financing offered on the lot is often a home-only loan. A land-home construction loan finances your home and land together as real property, with draws during setup. It takes a bit more paperwork, but you end up with a real mortgage on your home and land.

Do I make payments while my home is being set?

Usually, it's interest only on the money that has been drawn so far. Full payments begin once the home is finished. On VA loans, construction interest is typically built into the price. Your OTC Worksheet shows estimates for both stages.

What if my dealer hasn't done a one-time close before?

That's fine. We'll walk them through the approval steps and the draw schedule before closing. You're welcome to bring them into your free consultation.

Can you finance a home in a mobile home park or on rented land?

No. Our construction loans are for homes on land you own or are buying. Homes on rented land use a different kind of loan, and we'll let you know early if that's the better fit.

Your land. Your build. Let's talk it through.

A free consultation is 20 minutes. We cover your land, your eligibility, and the right loan structure. No application required.

Tennessee · Virginia · North Carolina · South Carolina · Georgia · Kentucky

Schedule a Free Consultation (opens in a new tab)

20 minutes · no application · no commitment

NewBuild is led by the Arrowood Team at Preferred Rate. 260+ five-star Google reviews.

Prefer to reach out directly?

(423) 406-1567 · newbuild@preferredrate.com