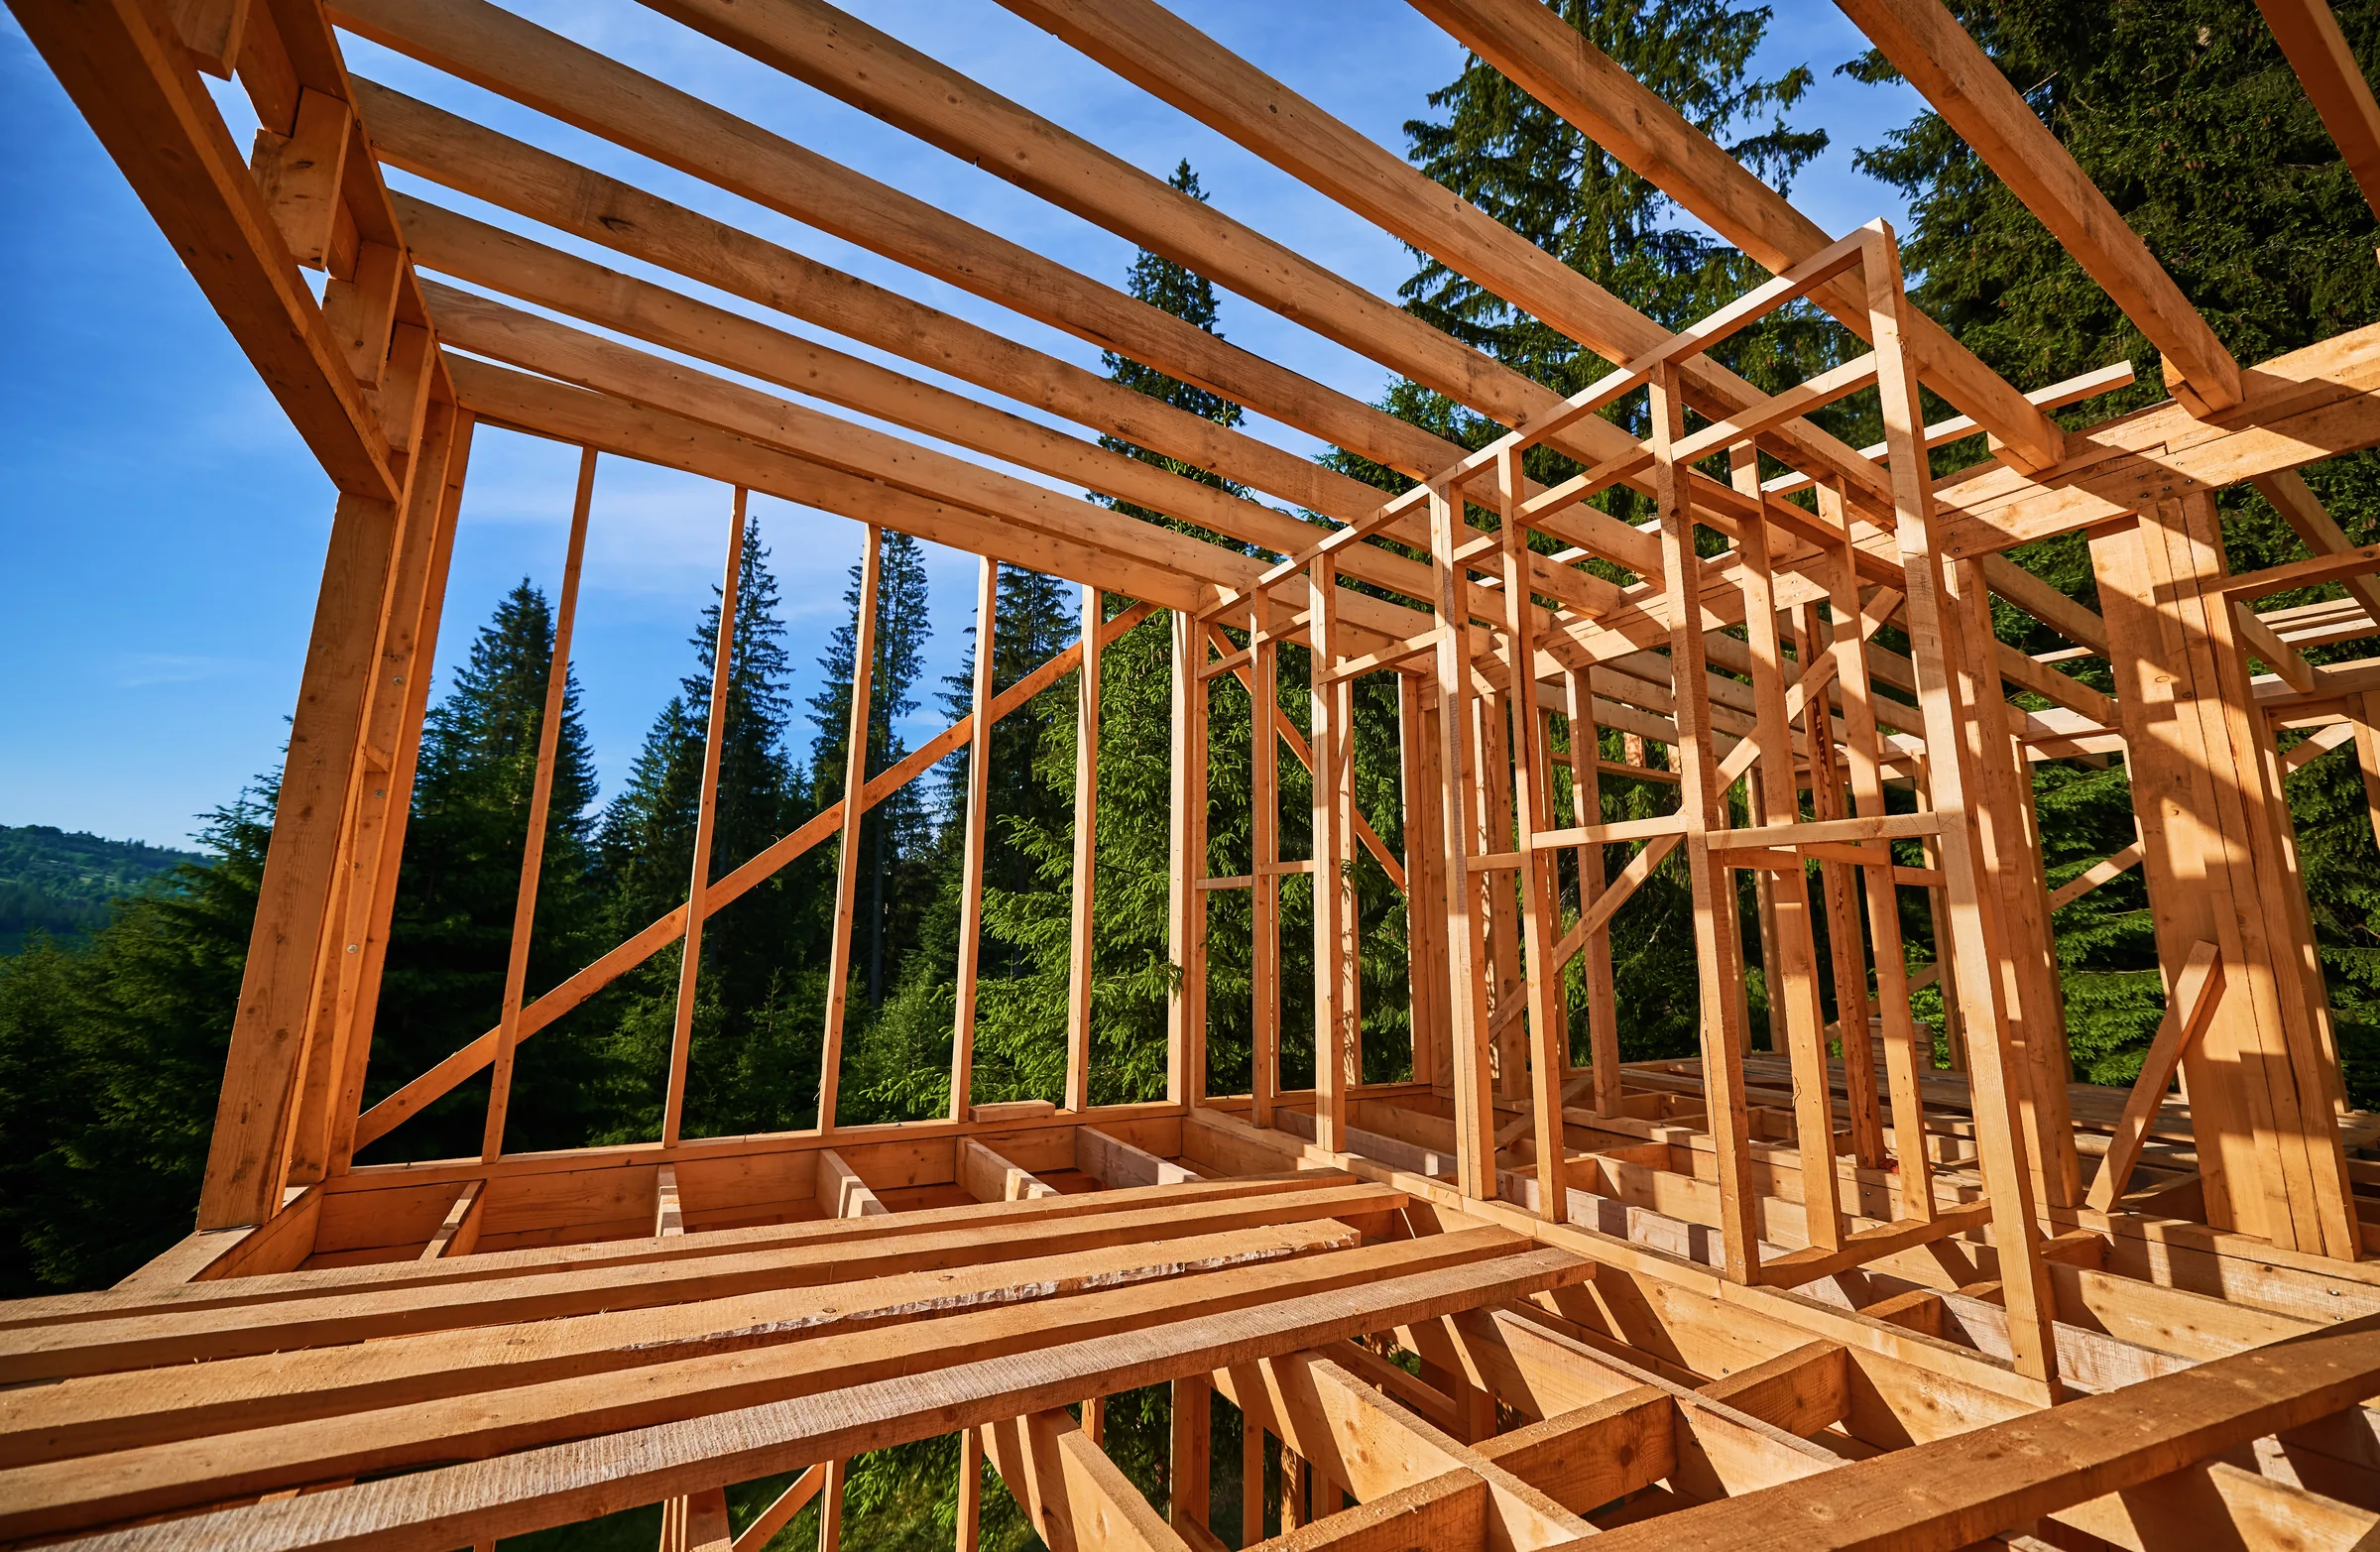
Land you already own
Equity in land you own can often count toward your down payment. Many of our clients have built this way.
Without a big down payment
You want a brand-new home without waiting years to save 20%. What you really need are two numbers: your monthly payment and your cash to close. Let's find them together.
The myth
Most people aren't searching for "FHA construction." They want a new home, maybe on family land or as a way out of a crowded rental. Then someone says they need 20% down, and they stop looking.
That's often wrong. FHA allows a smaller down payment, more room for other monthly debts, and flexible credit guidelines, so plenty of buyers with good credit choose it too. There's still a minimum down payment and mortgage insurance, and we'll walk through your actual numbers.
If you or your spouse served, start with veterans and active duty instead. VA may let you build with no down payment at all.
What surprises people
The builder or dealer price usually covers just the house. Foundation, well, septic, grading, driveway, utilities, and delivery for factory-built homes are the rest. That gap is where budgets break, so we never quote a payment from the house price alone.
We put your whole project into one picture before you commit, so the payment and cash to close you see are the real ones.
Real options
Your down payment doesn't have to come only from savings. Here are three ways our clients have done it:
Equity in land you own can often count toward your down payment. Many of our clients have built this way.
FHA allows down payment gifts from family. Many of our clients have used family gift funds to help build their first home.
Sometimes a dealer or builder can include closing costs in the price of the home. Your OTC Worksheet shows each item on its own line.
There's no one type of FHA buyer. Some want more room in their budget, others are still building savings or credit. We'll show you what's possible, and if now isn't the right time, what would need to change.
Every NewBuild loan follows the same six steps, from your first call to Move-In Day. It starts with a free consultation, and no house plans are needed.
Real builds
Three FHA one-time close loans we've closed, with three different down payment stories.
Barndominium · Chuckey, TN
As first-time buyers, Kay and Eddie used family gift funds for their down payment and built a roughly $331,000 barndominium with one FHA loan.
Kay and Eddie came to us as first-time homebuyers hoping to buy an existing home. They went under contract twice but weren't happy with what was available in their price range, so they started looking at building instead. After they found land, their first builder turned out to be unfamiliar with turnkey barndominiums and the draw process a construction loan requires, and eventually backed out. Rather than risk losing the property, they secured a land-only loan to buy it and used the extra time to handle some site prep themselves. They then partnered with Summertown Metals, closed on their FHA one-time-close loan using gift funds from family for the down payment, and have since moved in.
Modular · Tazewell, TN
Using the land they already owned as their down payment, Ken and Connie financed a roughly $327,000 modular home with one FHA loan.
Ken and Connie were ready to leave California and build on land they already owned in Tazewell, Tennessee. Working with Clayton Homes of Kingsport, they chose a modular home and started the financing process with a bank in Kentucky, but communication was poor and their calls eventually went unreturned. That's when they reached out to us. Since Connie works remotely, the move didn't mean giving up her job, and the couple handled much of the process from across the country. Their land's value served as their down payment rather than cash savings. They completed their FHA one-time-close loan, made the move east, and are now settled into their new home.
Manufactured · Rutledge, TN
Pete and Susan carved a homesite out of land they already owned and are building a roughly $284,000 manufactured home with one FHA loan.
Pete came to us through a referral after working with four or five manufactured home dealers before landing on Clayton Homes of Alcoa. He and Susan owned a few acres with a small, older home already on the property, so they had the land surveyed and divided off a portion for their new home to sit on. Underwriting and the appraisal went smoothly, but the new survey brought several county reviews and sign-offs that took longer than anyone expected. Nobody did anything wrong; the process simply took time. Pete and Susan are now under construction on their FHA one-time-close loan.
Names have been changed to protect client privacy. Loan amounts and details are real but reflect each borrower's individual credit, income, and underwriting circumstances; results aren't typical or guaranteed for every applicant.
Your guide
A construction loan has more moving parts than a regular purchase. Our five-person team handles all of it, from your first call to your final draw.
Your home
FHA works for site-built, modular, manufactured, and barndominium-style homes that meet the program's requirements, whether with a local builder or on land you own or are buying.
FHA has a county loan limit. In most of the counties we serve, it's $541,287 for a one-unit home in 2026, covering land, home, and site work. If your project is larger, we'll look at conventional or VA.
A home on rented land, like in a mobile home park, is financed differently, so it isn't a fit for this loan.
Related situations: Site-built home Manufactured home You already own the land Land and home together First time building
FAQ
Often, yes. FHA construction loans are designed for a smaller down payment. During your free consultation, we'll look at your savings, your land, and your full project, and show you what it takes.
Those are the two numbers that matter most, and we can only give you real ones once the home, the land, the site work, and your loan program are in one picture. We estimate both on your first call. The cost planner gives you an early sketch before then.
Our minimum credit score for FHA construction is 580. Your full picture matters too, including your income, your debts, and your down payment. Bring us the facts, and if now isn't the time, you'll leave knowing what would need to change.
Yes. FHA allows down payment gifts from family members, with the right paperwork. Kay and Eddie built their first home this way.
Site-built homes, modular homes, manufactured homes on a permanent foundation, and barndominium-style homes can all work, as long as the property meets FHA's requirements. A home on rented land, like in a mobile home park, is a different kind of loan.
A free consultation is 20 minutes. We cover your land, your eligibility, and the right loan structure. No application required.
Tennessee · Virginia · North Carolina · South Carolina · Georgia · Kentucky
20 minutes · no application · no commitment
NewBuild is led by the Arrowood Team at Preferred Rate. 260+ five-star Google reviews.
Prefer to reach out directly?