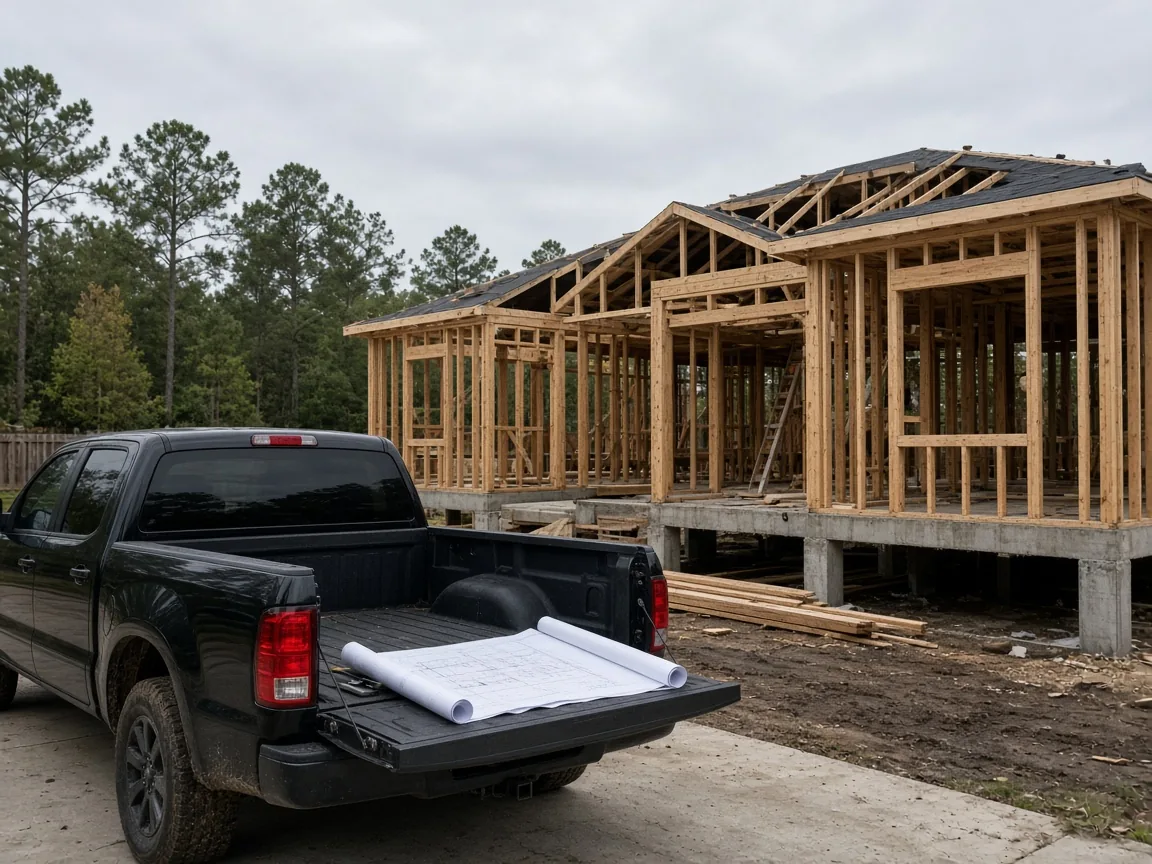
Know before the deposit
Send the buyer before you take a design deposit. We tell you whether they can close on your contract, so you are not building a relationship on a guess.
For site-built home builders
Qualify the buyer before the deposit gets spent, and keep the draws moving once the job starts.
Know early whether your buyer can close on your contract
Draws released as each phase is completed and inspected
A team that stays with you through the final draw
or call (423) 406-1567
The situation
A buyer walks in with a pre-approval letter and a lot. But a purchase pre-approval isn't a construction loan structure, and finding that out after the design deposit is spent costs everyone time and money.
Then there's the build itself. Some lenders qualify the buyer and disappear when the first inspection is due. When draws run slow, your subs wait, your schedule slips, and you end up explaining the loan to your own customer.
We explain first, then we stay. And we won't go around you to the buyer with a different story than the one you sold.
What this changes
Send the buyer before you take a design deposit. We tell you whether they can close on your contract, so you are not building a relationship on a guess.
Predictable requirements beat surprise holdbacks. A dedicated construction person works the draws, so you are not teaching the loan again every cycle.
Your buyer remembers who sent them to us. A smooth loan makes you look good, from the first call to the final draw.
How we work with builders
Proof
Custom site-built · Jonesborough, TN
Scott Britton Construction (opens in a new tab) built a roughly $560,000 custom home for a veteran couple on land they already owned, financed with one VA one-time-close loan.
Read their story →Barndominium · Chuckey, TN
Summertown Metals (opens in a new tab) built a roughly $331,000 barndominium for first-time buyers, after their first builder, unfamiliar with construction draws, backed out.
Read their story →Individual results vary. Loan amounts are real but reflect each borrower's individual circumstances.
The plan
Before the design deposit. If they own land or are buying some, send them our way.
We'll come back with whether they can close on your contract and what the loan needs from the build.
Each draw is released as the work is completed and inspected, and we stay in contact with you throughout.
Run a deal by us
A buyer with a purchase pre-approval who wants to build. Land that needs a survey or a split. A custom plan, a barndominium, or a credit picture you're not sure about. Tell us the situation, and we'll give you an honest read on whether it can work and what it would take.
No names or paperwork needed. Just the situation.
Describe the situation in a few sentences. We'll get back to you with an honest read.
The agreement
If it's a path we can do, we'll tell you what it takes. If it isn't, we'll tell you that and point you toward what fits, rather than sitting on it.
You'll know who has the loan and what comes next, with updates as it moves, including funding updates you can forward to your manager.
We won't go to your buyer with a different story than the one you sold. If something isn't workable, you'll hear it while you can still redirect the job.
We stay engaged through delivery, setup, inspections, and the final draw.
All loans subject to approval. Equal Housing Lender.
Programs
VA is usually where the conversation starts. We also do FHA and conventional one-time close.
Usually where the conversation starts. Eligibility, entitlement, and construction-period interest handled up front. Subject to full qualification. VA construction loans.
For the buyer building without a large down payment. Down payment figures refer to the down payment only; closing costs and prepaids still apply. FHA construction.
For the buyer with credit and a down payment in hand. Conventional construction.
Send them before they go looking. We'll work up what they may qualify for, so they know the total and what's left over for land and site prep. A buyer shopping with a number in hand tends to find something that works.
Subject to full qualification.
Who you're working with
The same small team works every loan you send us, from the first call to the final draw. You'll never be explaining a deal to someone new, and nobody will bounce you around.
Tim Arrowood (NMLS #393468), who leads the team, will also sit down with you and your team to walk through how these loans work, so you can explain them to your buyers with confidence. No charge and no pitch.
Available 8:30 AM to 6 PM, Monday to Friday · (423) 406-1567
FAQ
Send us a buyer
If your buyer owns land or is buying some, and it's anywhere close to a one-time close, send them to us. We'll sort out which way it should go. That's our job, not yours.
Your message reaches the whole team, so it isn't sitting with one person. Read client and partner reviews.
We just need enough to reach your buyer. You don't need to sort anything out first; we'll take it from here.
All loans subject to approval.