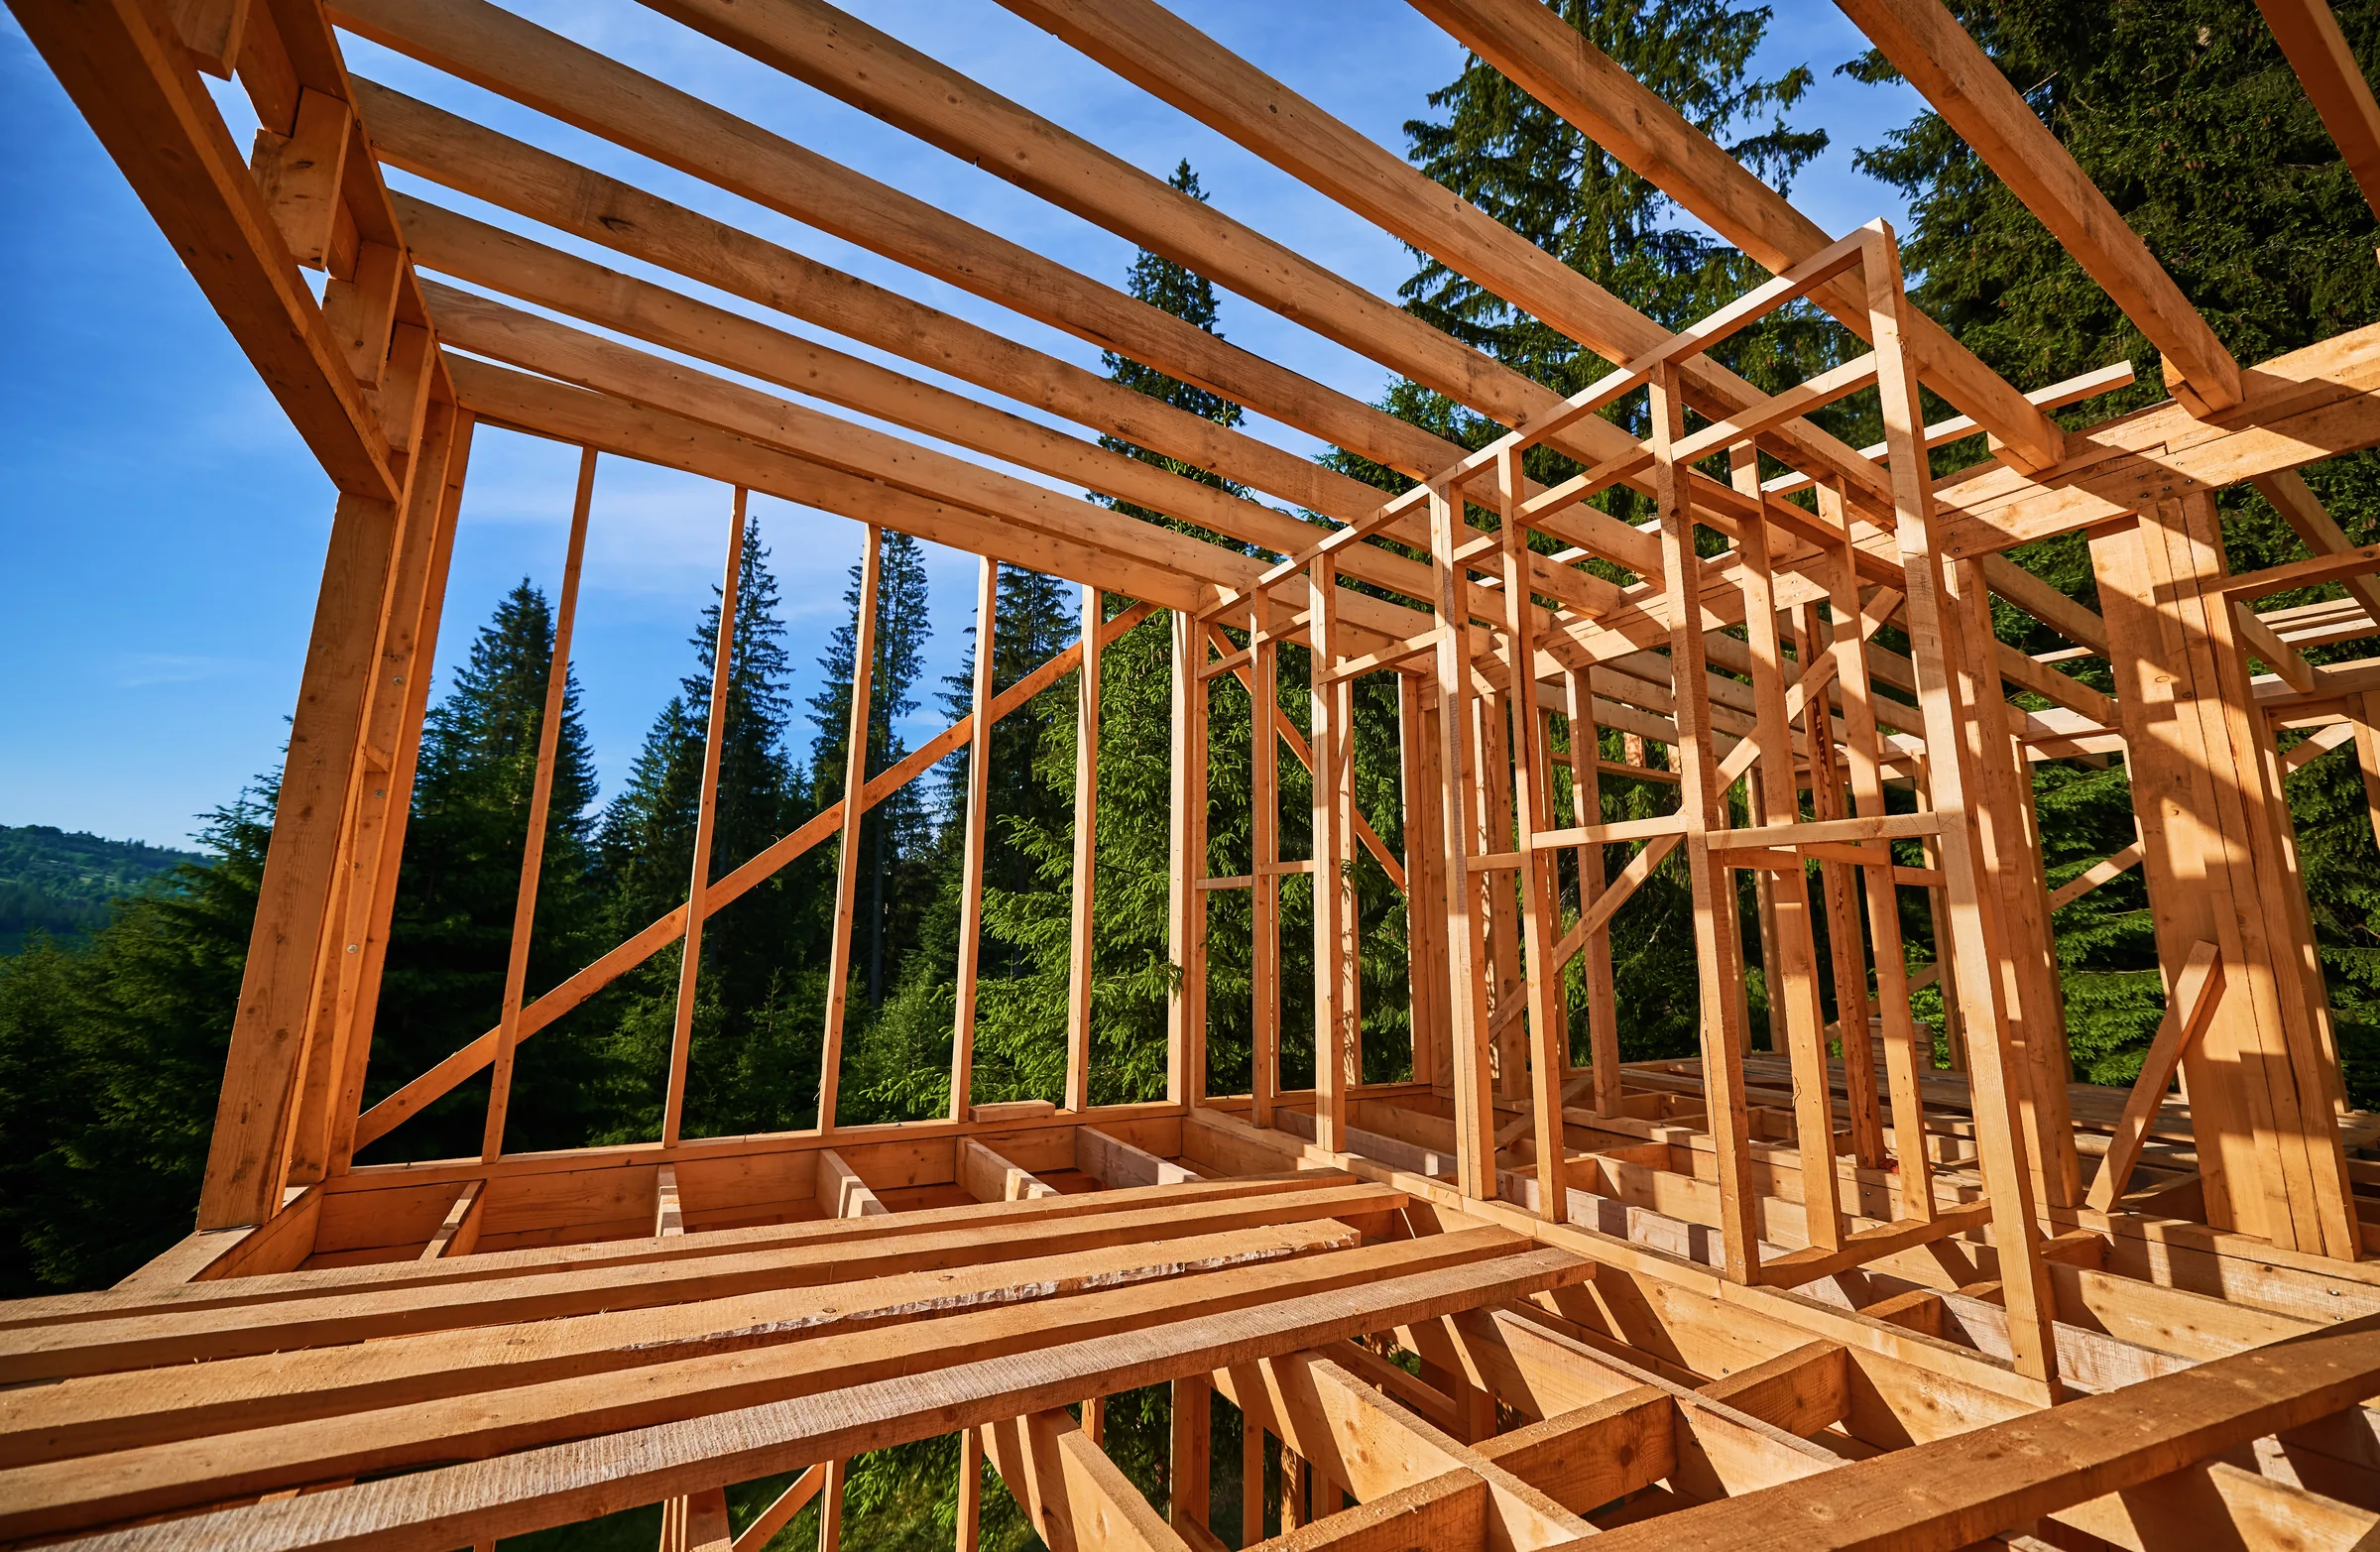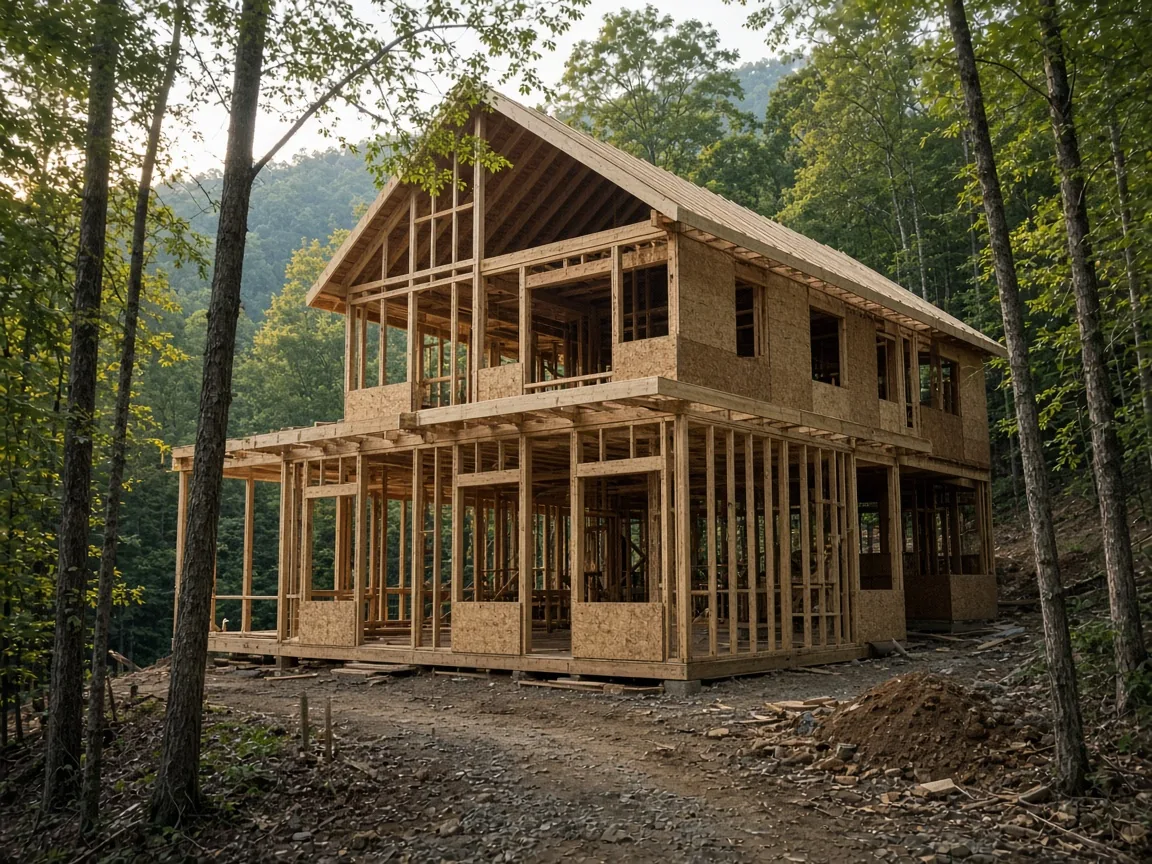
A stick-built home at the framing stage in East Tennessee woods

Site-built home

A site-built home, from modest to custom.

Whether it's a modest home on family land or a custom home with a view, we finance site-built homes with one loan and one closing, and we stay with you and your builder through the final draw.

Modest to customSite-built homes of every size
Builder reviewDone early, so nothing stalls
Draws as you buildReleased as each phase is done
Six statesTN · VA · NC · SC · GA · KY

Two kinds of builds

Every site-built home starts with a plan

Some clients build a custom home on land they own. Others build a modest site-built home because a factory floor plan didn't fit.

Either way, the same things matter: a solid contract, a builder who can be approved, draws that match the work, and a finished value that supports what you're spending.

What to watch for

When the bids keep climbing

Custom homes have a way of growing. Allowances run over, the plans miss a detail, or a steep lot needs more site work than expected. A loan based on last month's number can't quietly absorb a new addition.

Tell us when your project changes, so we can adjust the loan with you before it becomes a problem.

How we help

What we review on a site-built home

Before you commit, we look at the whole project with you:

  • The contract. A fixed price, with clear allowances and who pays for what.
  • Your builder. Their licensing, insurance, track record, and paperwork.
  • The draw schedule. Funds released as each phase of the work is completed and inspected.
  • Site work. Grading, driveway, well, and septic, especially on steep mountain lots.
  • The finished value. Whether the completed home is likely to appraise for enough to support the project.
  • The size of the loan. Loan limits apply to the loan amount, not your total cost, so a larger down payment can support a larger home.

Building something larger or longer? A two-time close, our conventional option that requires at least 10% down, can be a good fit for bigger projects.

One thing to know early: owner-builder arrangements aren't eligible, so your home needs to be built by a licensed builder.

The NewBuild System

Your site-built home, step by step

Every NewBuild loan follows the same six steps, from your first call to Move-In Day. It starts with a free consultation, and no house plans are needed.

  1. Build Plan Consultation

  2. Pre-Approval

  3. Plan and Contract Review

  4. Loan Closing

  5. Construction

  6. Move-In Day

Real builds

A custom site-built home we financed

Mike and Brenda built a custom home on land they already owned, with Scott Britton Construction.

Site-built · Jonesborough, TN

A 62.5% debt ratio didn't automatically end their plans to build.

With a 651 credit score and a roughly 62.5% debt ratio, they used VA underwriting to finance a roughly $560,000 custom build on land they already owned.

Read their story

Mike and Brenda weren't sure a VA one-time-close loan was even available until a banker friend referred them to us. They owned their land and wanted to build a custom home before selling their existing house, but a 651 credit score and roughly 62.5% debt-to-income ratio made traditional financing difficult. Using the flexibility of VA underwriting, they secured a roughly $560,000 one-time-close construction loan and completed the home. They've since moved in, listed their previous house, and plan to use the sale proceeds to pay down consumer debt and their new mortgage.
Mike and Brenda C. · VA one-time-close construction borrowers, Jonesborough, TN · Builder: Scott Britton Construction (opens in a new tab)

Names have been changed to protect client privacy. Loan amounts and details are real but reflect each borrower's individual credit, income, and underwriting circumstances; results aren't typical or guaranteed for every applicant.

Your guide

One team, start to finish

  • Tim Arrowood
  • Cindy Faulkner
  • Kevin Cooper
  • Rhonda Hendrix
  • Amy Lay

A site-built home has more moving parts than a regular purchase. Our five-person team handles all of it and works directly with your builder.

260+ five-star reviews Since 2023 closing one-time close loans Our team stays with you through every draw

Your loan program

Any of our programs can work

VA, FHA, and conventional loans can all finance a site-built home. Building a post-frame or metal-shell home? See barndominium construction loans.

Related situations: Barndominium Good credit and a down payment Veterans You already own the land

FAQ

Frequently asked questions

Can I be my own builder?

Not with our construction loans. Owner-builder arrangements aren't eligible, so your home needs to be built by a licensed builder under a construction contract.

Does my builder need to be approved?

Yes. Early on, we review your builder's licensing, insurance, track record, and paperwork, so nothing holds up your loan later. We review the documentation; judging their workmanship is up to you.

What if the bids keep climbing after we talk?

Tell us right away. A loan based on an older number won't automatically cover a bigger project. It's much easier to adjust the plan early than to hope the appraisal comes in high.

Is there a limit on how big my project can be?

Loan limits apply to the loan amount, not your total project cost, so a larger down payment can support a larger home. For bigger or longer builds, a two-time close, which requires at least 10% down, may be a good fit.

What about a barndominium?

We finance those too. They come with a few extra questions, especially around the appraisal. See barndominium construction loans.

Your land. Your build. Let's talk it through.

A free consultation is 20 minutes. We cover your land, your eligibility, and the right loan structure. No application required.

Tennessee · Virginia · North Carolina · South Carolina · Georgia · Kentucky

Schedule a Free Consultation (opens in a new tab)

20 minutes · no application · no commitment

NewBuild is led by the Arrowood Team at Preferred Rate. 260+ five-star Google reviews.

Prefer to reach out directly?

(423) 406-1567 · newbuild@preferredrate.com